1. What Is a Personal Loan?
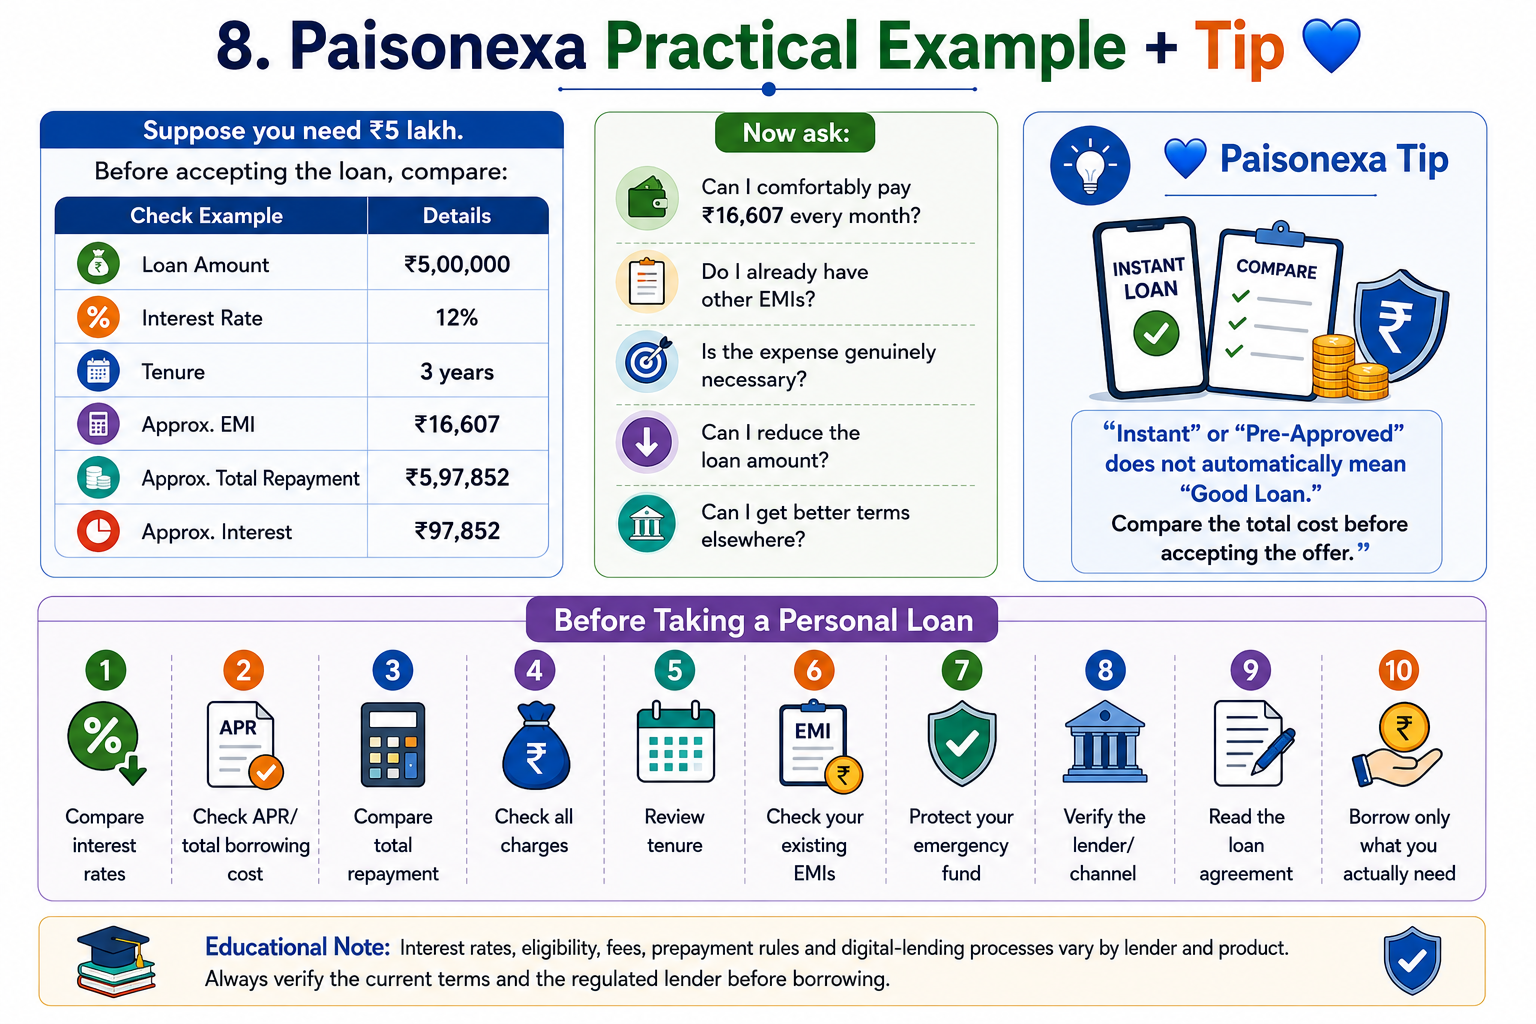
A personal loan is an unsecured loan offered by a bank or financial institution for eligible personal needs.
Unlike a home or car loan, it generally does not require a specific asset as collateral.
Common uses include:
- Medical or emergency expenses
- Education-related expenses
- Home repairs
- Major planned expenses
- Debt consolidation, where financially appropriate
Because it is generally unsecured, personal loans can carry higher interest rates than some secured loans.
Easy access does not mean low-cost borrowing. Always compare the total repayment cost.
2. How Does a Personal Loan Work?
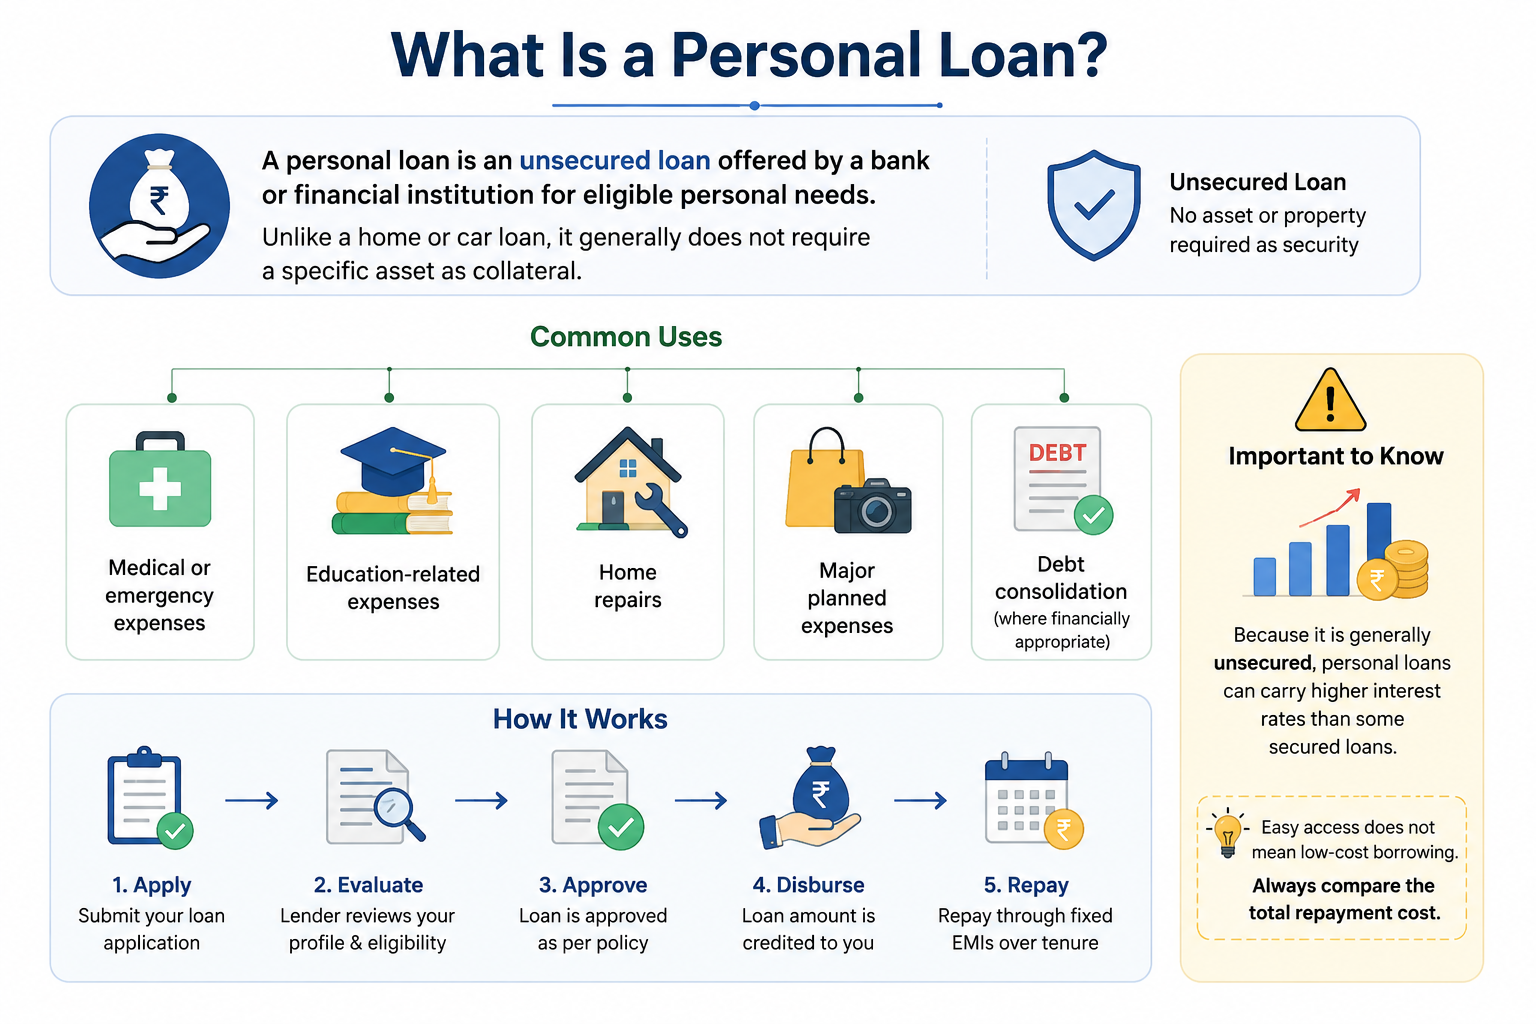
The basic process is:
Application → Eligibility Check → Approval → Disbursement → EMI Repayment
Your EMI generally contains:
Principal + Interest
The EMI mainly depends on:
- Loan amount
- Interest rate
- Tenure
Simple Example
Suppose you borrow ₹5,00,000.
The lender charges interest according to the agreed terms, and you repay the loan through scheduled EMIs until the outstanding amount is cleared.
A longer tenure can reduce the EMI but may increase the total interest paid.
3. Digital Personal Loan — How Does It Work?
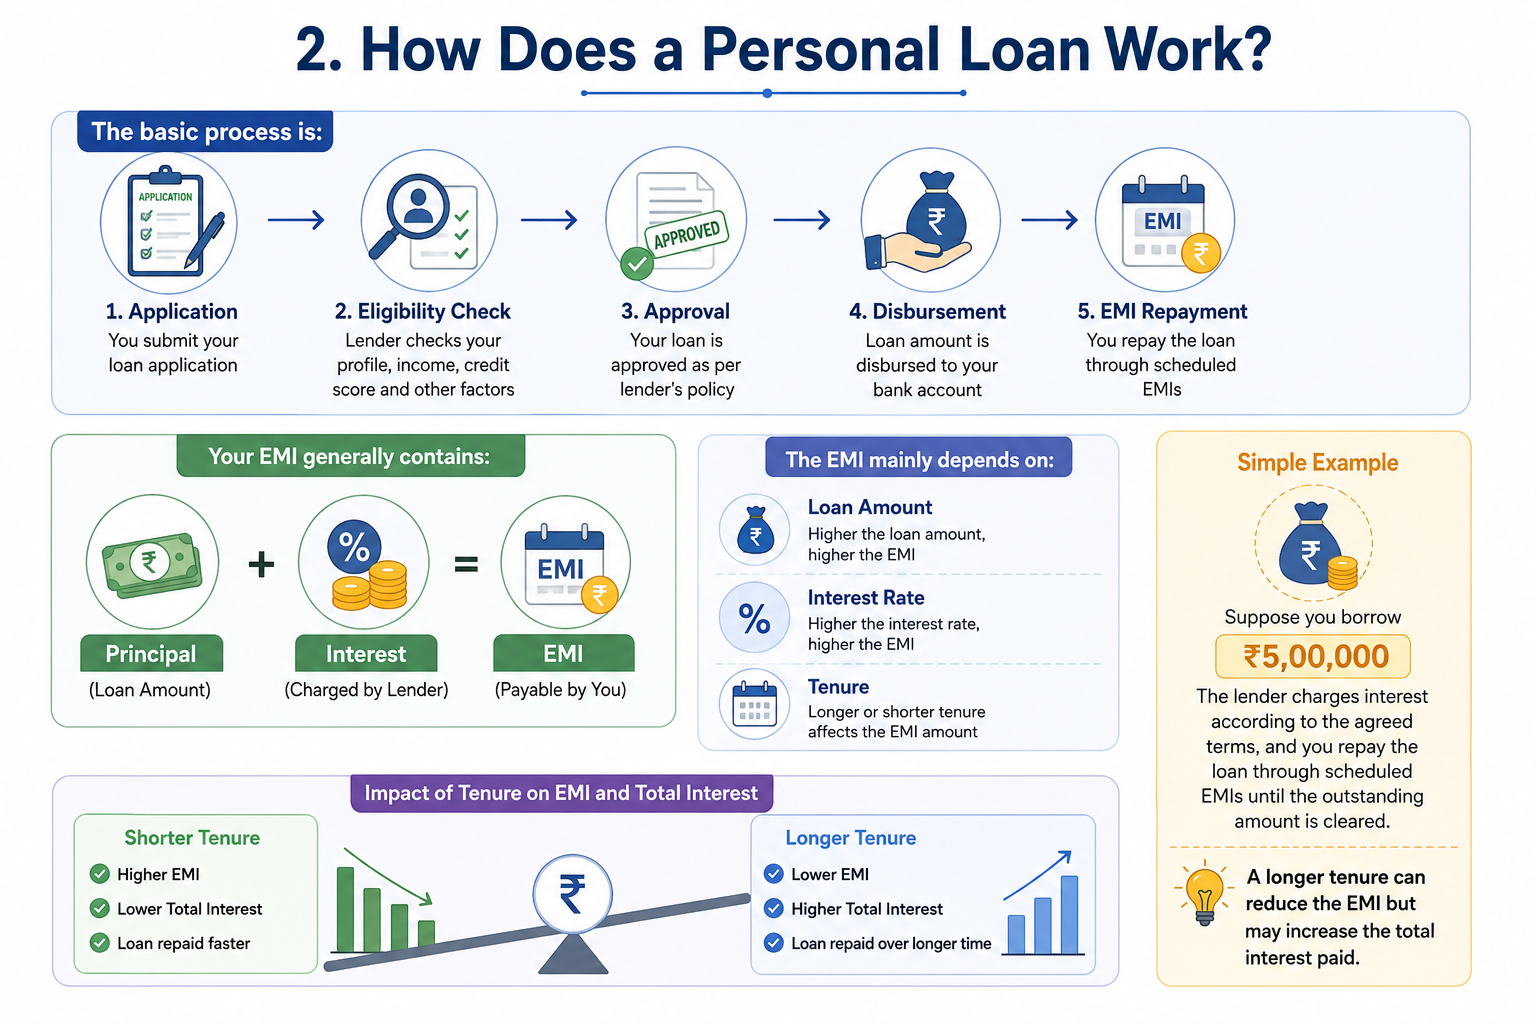
A Digital Personal Loan is a personal-loan process where application, verification and other steps are completed largely through a bank/NBFC’s digital channel or an associated lending service provider.
Typical Digital Process
Apply Online → KYC → Credit Assessment → Loan Offer → Accept Terms → e-Sign/Documentation → Disbursement → EMI
The lender may digitally assess information such as:
- Identity
- Income
- Credit history
- Existing obligations
- Repayment capacity
For digital lending, RBI requires regulated entities to disclose the loan’s all-inclusive cost as Annual Percentage Rate (APR) and has requirements around data collection, consent and privacy.
What Is a Pre-Approved / Personalised Offer?
Sometimes an existing customer may see an offer such as:
“You are eligible for a personal loan up to ₹5 lakh.”
This may be based on information available to the lender and its internal credit criteria.
Important:
Pre-approved does not necessarily mean guaranteed.
The final amount, rate and terms can still depend on verification and applicable conditions.
Before Accepting a Digital Loan
Check:
Loan Amount → APR/Total Cost → Interest Rate → EMI → Tenure → Processing Fee → Other Charges → Prepayment Terms
Also verify that you are dealing with the regulated lender or its authorised digital lending channel/service provider.
4. When Should You Take a Personal Loan?
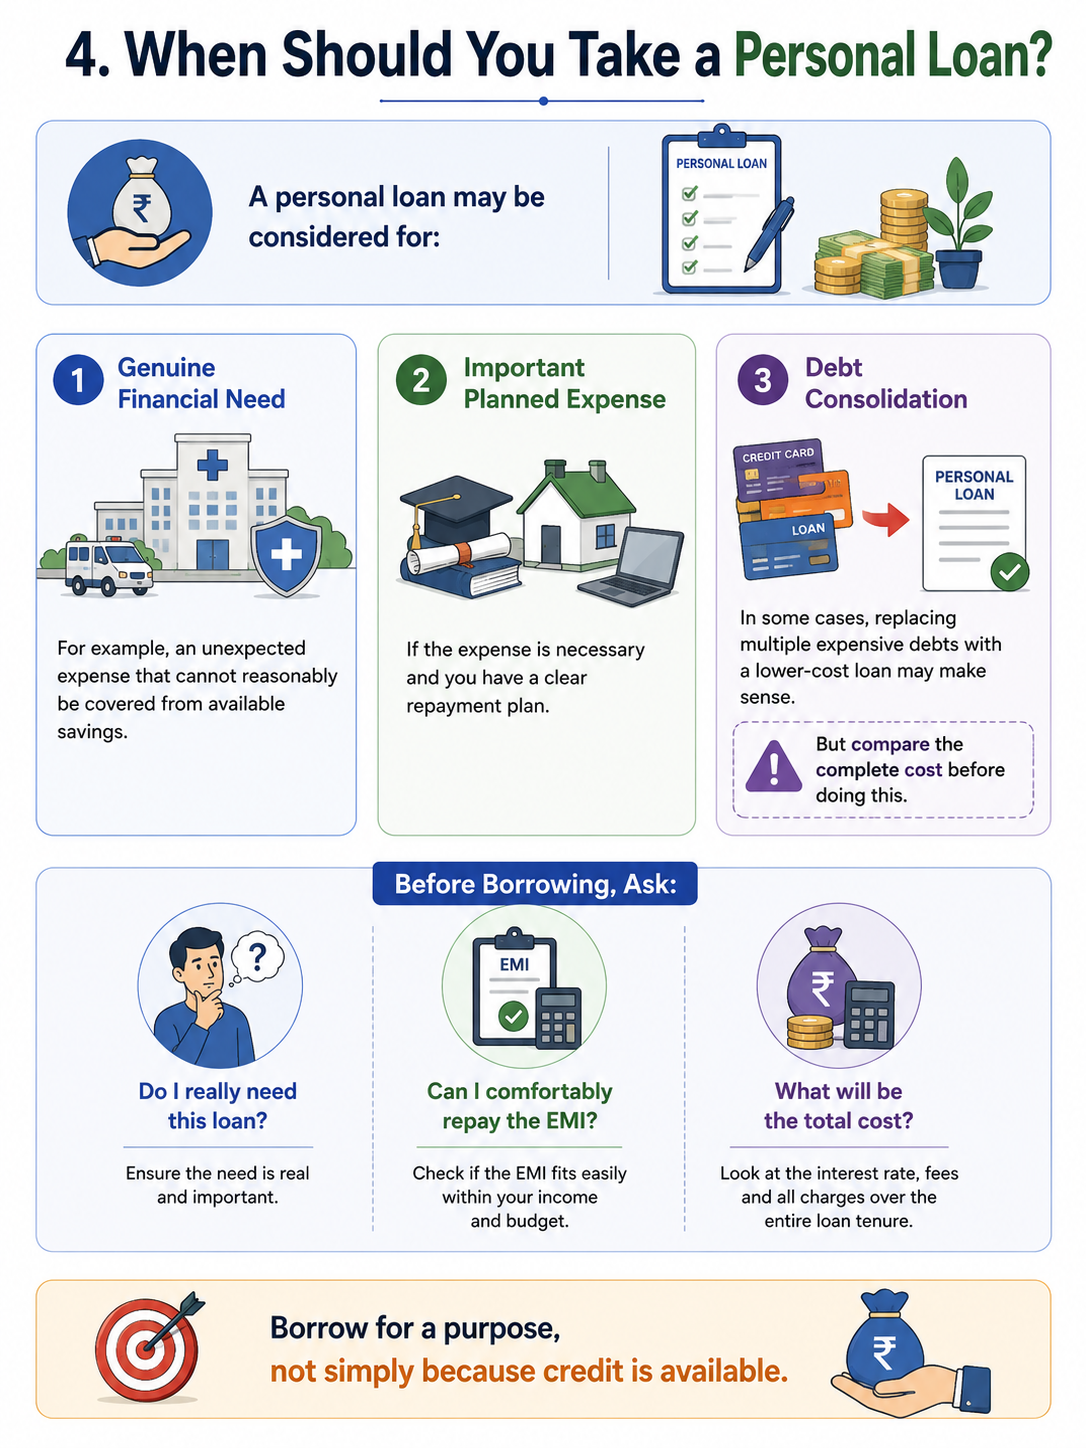
A personal loan may be considered for:
Genuine Financial Need
For example, an unexpected expense that cannot reasonably be covered from available savings.
Important Planned Expense
If the expense is necessary and you have a clear repayment plan.
Debt Consolidation
In some cases, replacing multiple expensive debts with a lower-cost loan may make sense.
But compare the complete cost before doing this.
Before Borrowing, Ask:
Do I really need this loan?
Can I comfortably repay the EMI?
What will be the total cost?
Borrow for a purpose, not simply because credit is available.
5. When Should You Avoid a Personal Loan?
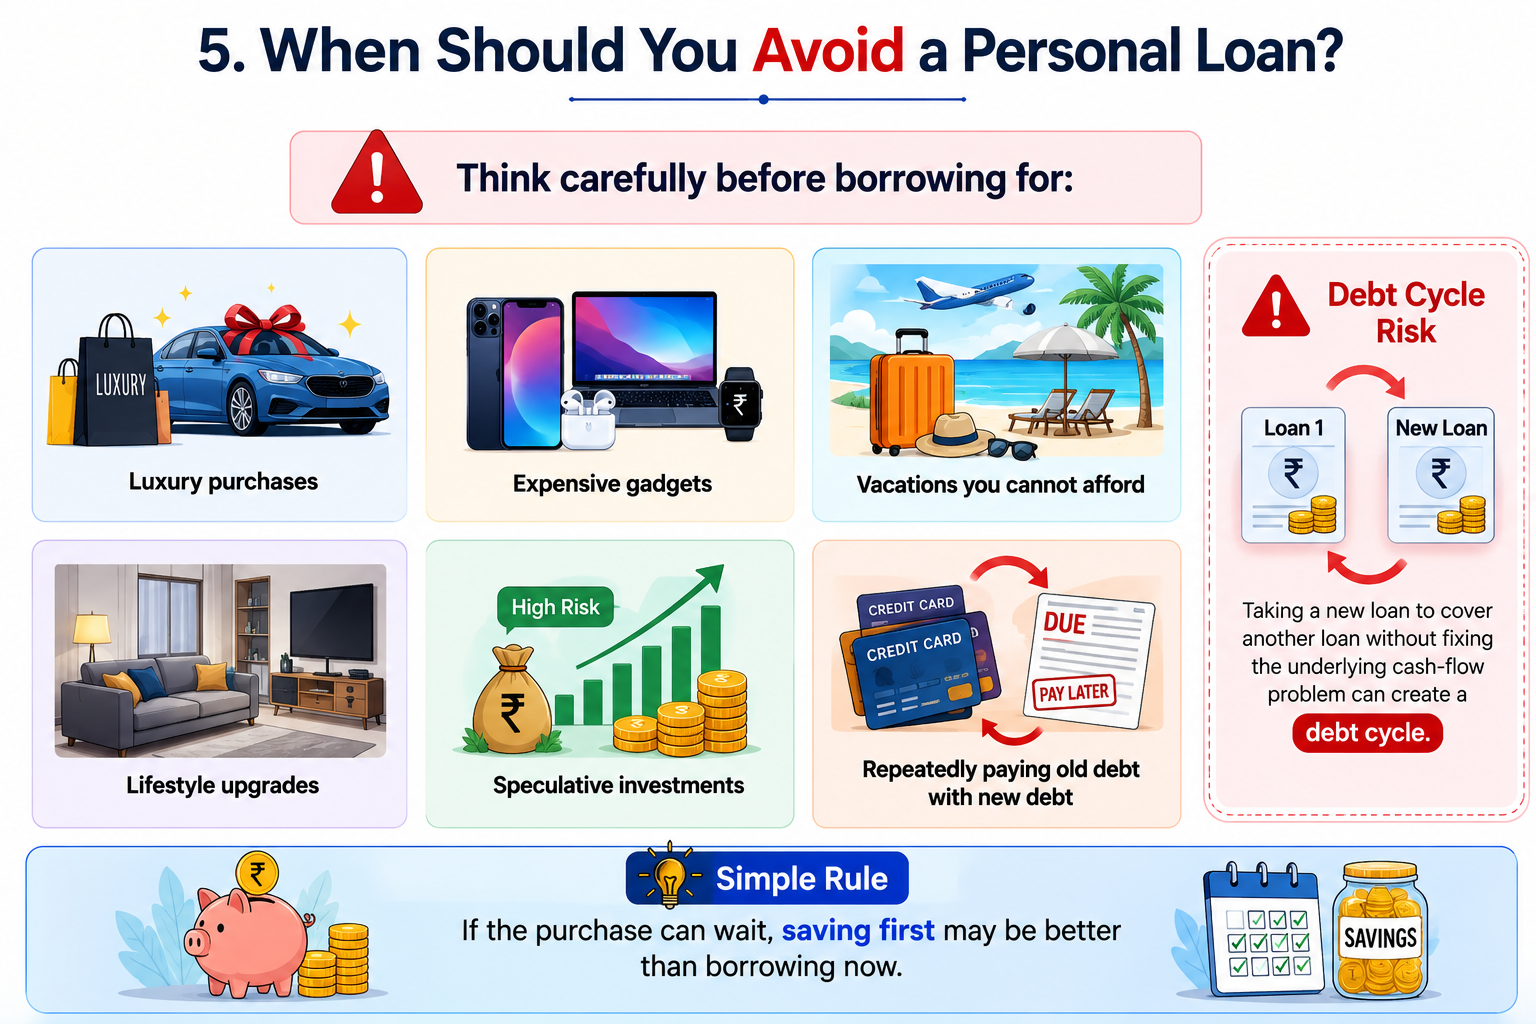
Think carefully before borrowing for:
- Luxury purchases
- Expensive gadgets
- Vacations you cannot afford
- Lifestyle upgrades
- Speculative investments
- Repeatedly paying old debt with new debt
Taking a new loan to cover another loan without fixing the underlying cash-flow problem can create a debt cycle.
Simple Rule
If the purchase can wait, saving first may be better than borrowing now.
6. Interest Rate, EMI & Total Cost
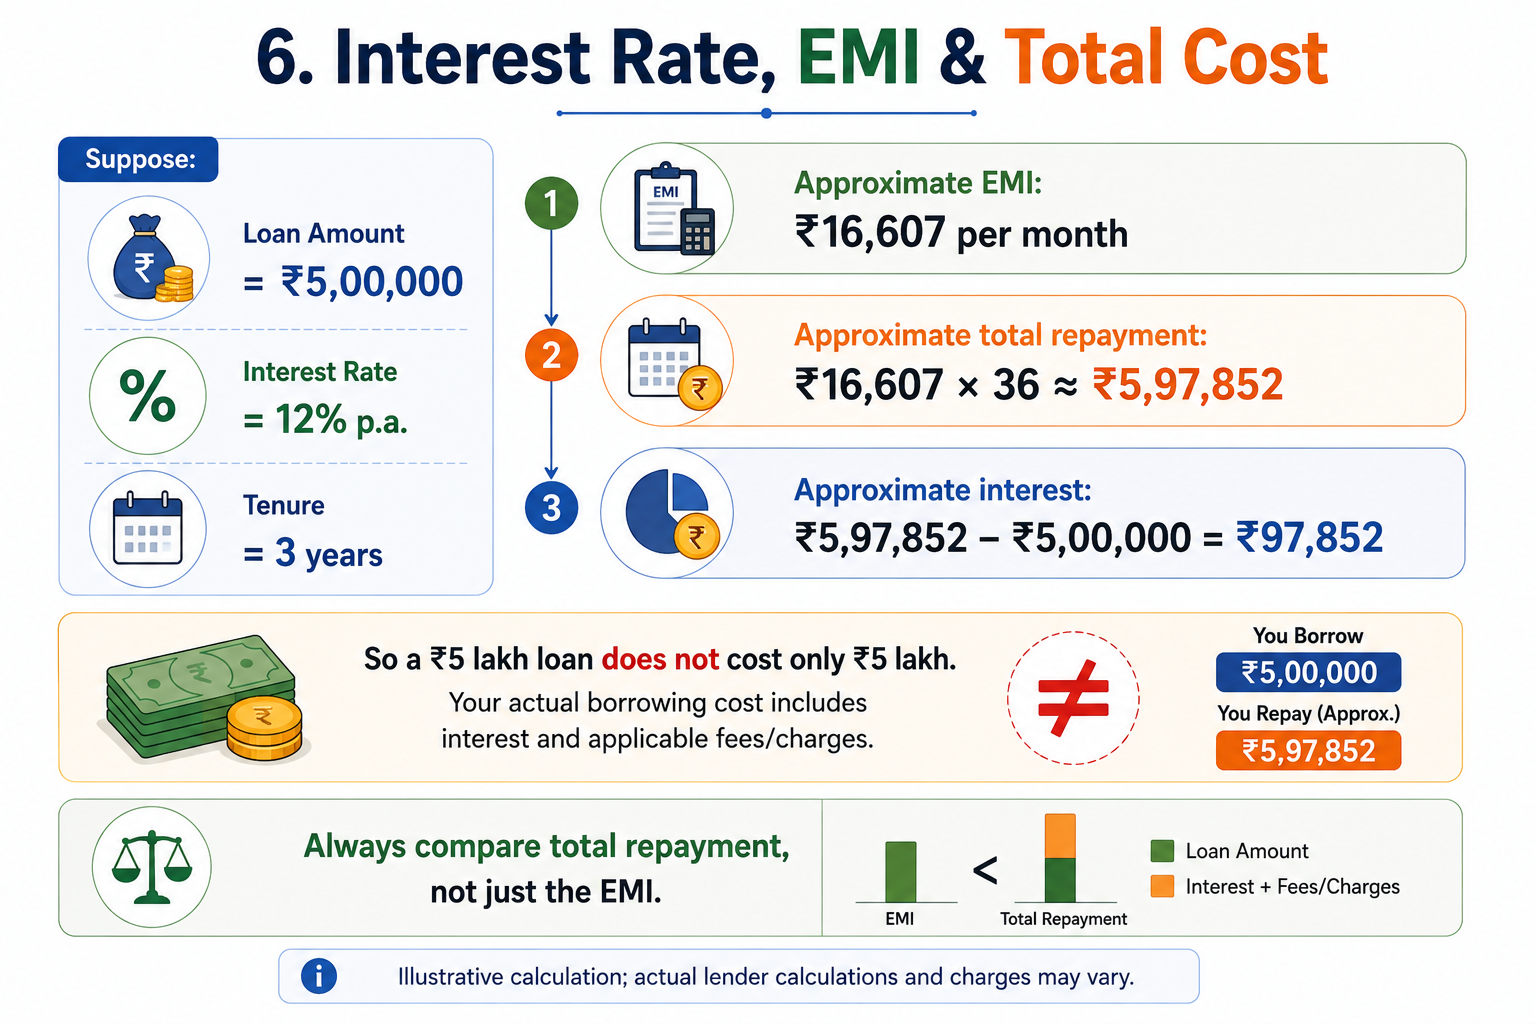
Suppose:
Loan Amount = ₹5,00,000
Interest Rate = 12% p.a.
Tenure = 3 years
Approximate EMI:
₹16,607 per month
Approximate total repayment:
₹16,607 × 36 ≈ ₹5,97,852
Approximate interest:
₹5,97,852 − ₹5,00,000 = ₹97,852
So a ₹5 lakh loan does not cost only ₹5 lakh.
Your actual borrowing cost includes interest and applicable fees/charges.
Always compare total repayment, not just the EMI.
Illustrative calculation; actual lender calculations and charges may vary.
7. Eligibility, Charges & How to Reduce Cost
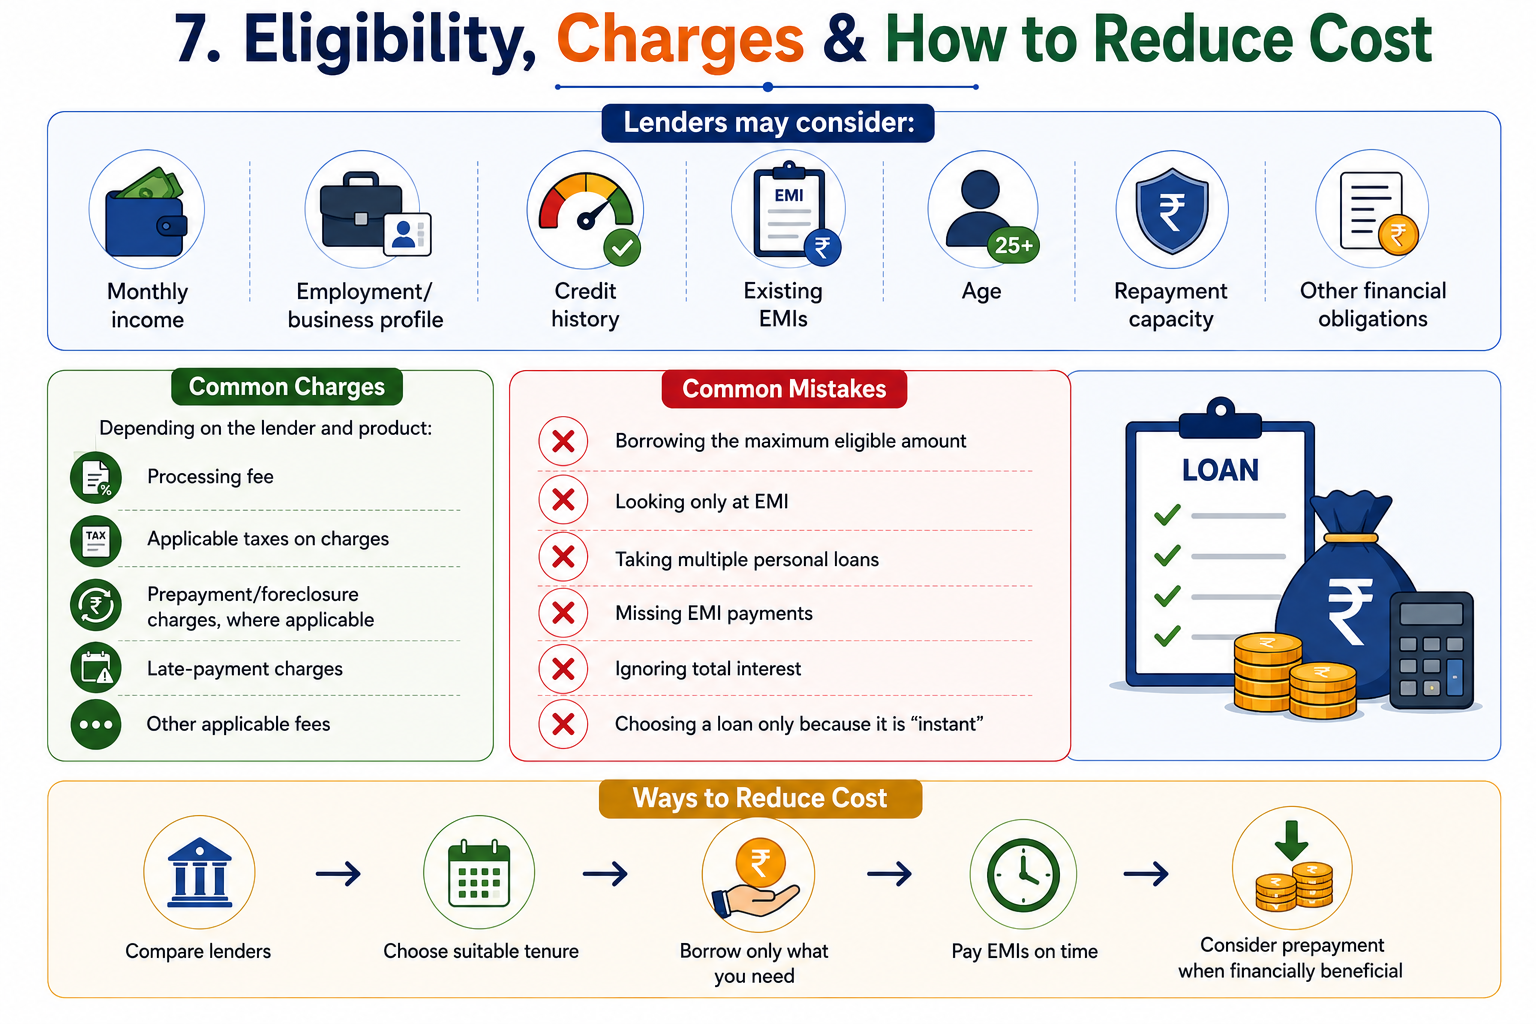
Lenders may consider:
- Monthly income
- Employment/business profile
- Credit history
- Existing EMIs
- Age
- Repayment capacity
- Other financial obligations
Common Charges
Depending on the lender and product:
- Processing fee
- Applicable taxes on charges
- Prepayment/foreclosure charges, where applicable
- Late-payment charges
- Other applicable fees
Common Mistakes
❌ Borrowing the maximum eligible amount
❌ Looking only at EMI
❌ Taking multiple personal loans
❌ Missing EMI payments
❌ Ignoring total interest
❌ Choosing a loan only because it is “instant”
Ways to Reduce Cost
Compare lenders → Choose suitable tenure → Borrow only what you need → Pay EMIs on time → Consider prepayment when financially beneficial
8. Paisonexa Practical Example + Tip 💙
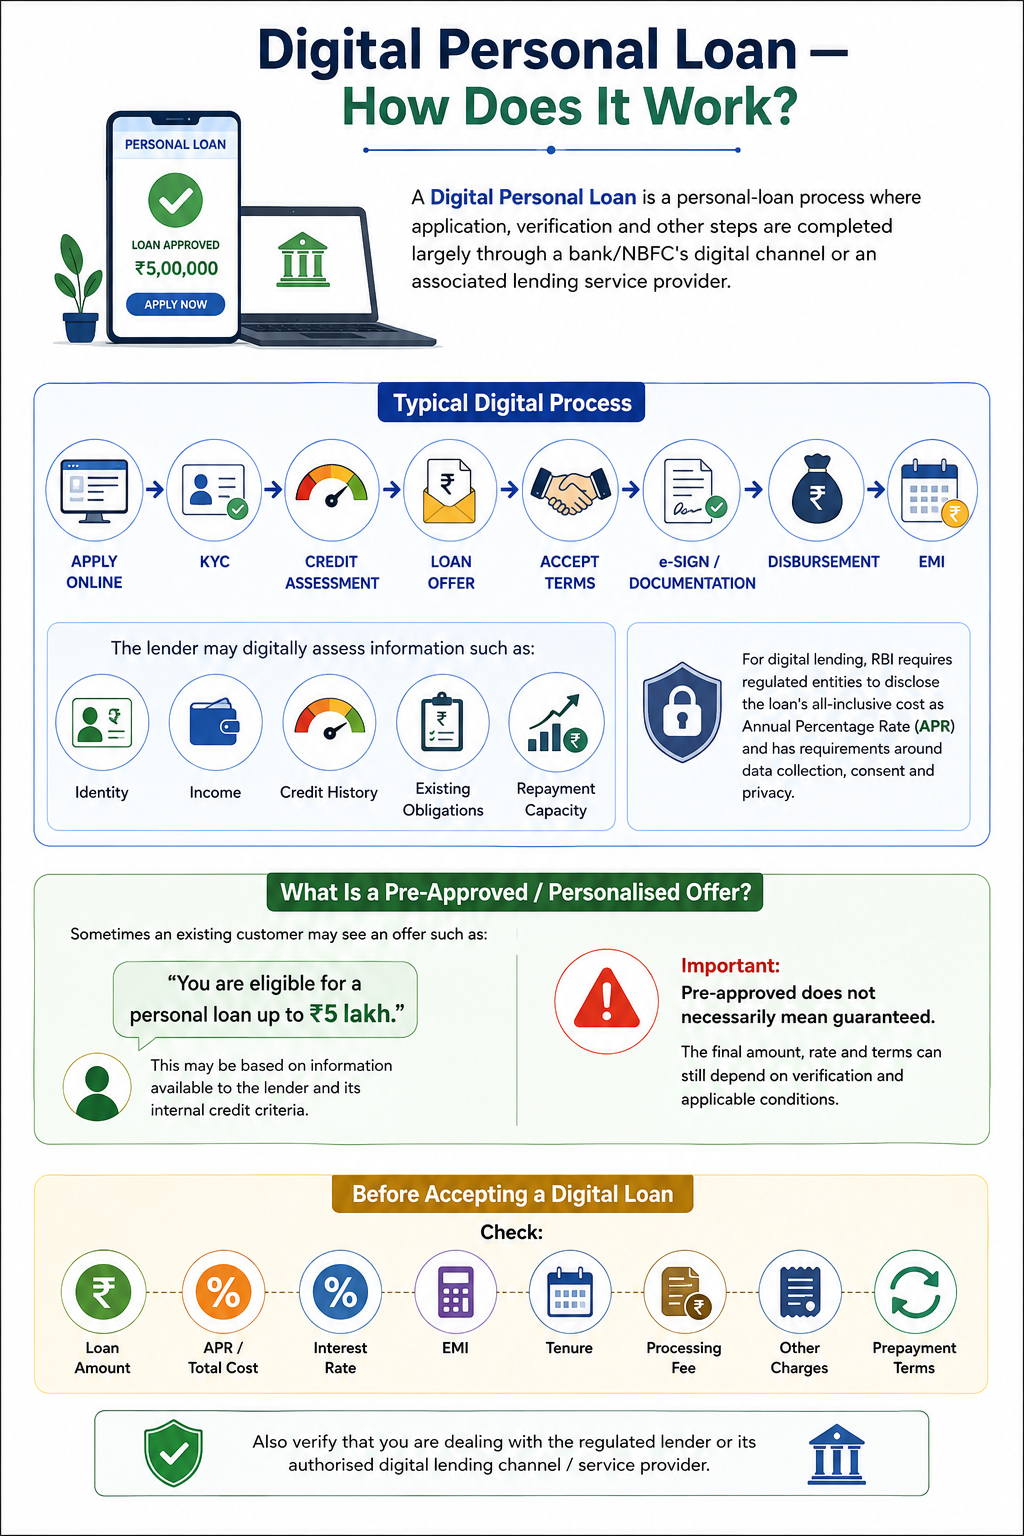
Suppose you need ₹5 lakh.
Before accepting the loan, compare:
| Check | Example |
|---|---|
| Loan Amount | ₹5,00,000 |
| Interest Rate | 12% |
| Tenure | 3 years |
| Approx. EMI | ₹16,607 |
| Approx. Total Repayment | ₹5,97,852 |
| Approx. Interest | ₹97,852 |
Now ask:
Can I comfortably pay ₹16,607 every month?
Do I already have other EMIs?
Is the expense genuinely necessary?
Can I reduce the loan amount?
Can I get better terms elsewhere?
💙 Paisonexa Tip
“Instant” or “Pre-Approved” does not automatically mean “Good Loan.” Compare the total cost before accepting the offer.
Before Taking a Personal Loan
☑ Compare interest rates
☑ Check APR/total borrowing cost
☑ Compare total repayment
☑ Check all charges
☑ Review tenure
☑ Check your existing EMIs
☑ Protect your emergency fund
☑ Verify the lender/channel
☑ Read the loan agreement
☑ Borrow only what you actually need
Educational Note: Interest rates, eligibility, fees, prepayment rules and digital-lending processes vary by lender and product. Always verify the current terms and the regulated lender before borrowing.