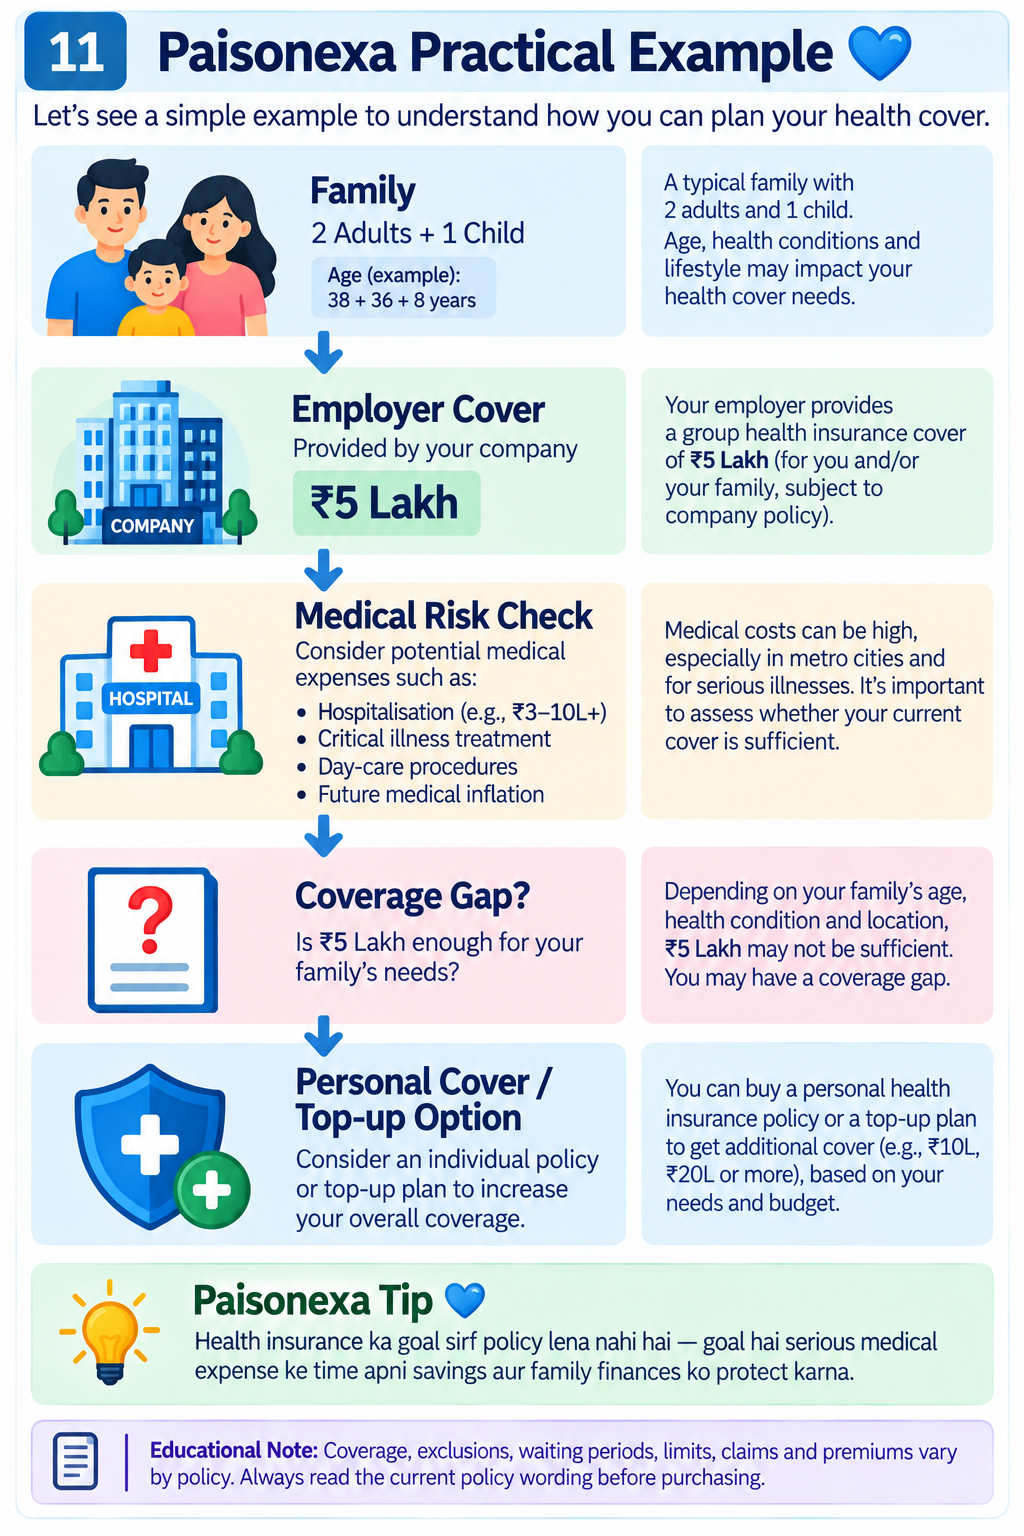
1. What Is Health Insurance?
Health insurance helps cover eligible medical and hospitalisation expenses in exchange for a premium, according to the policy terms.
🛡️ Health Insurance Flow
💳 Premium → 🛡️ Health Cover → 🏥 Hospitalisation → 📋 Claim → 💰 Financial Protection
Main purpose: medical emergency ke time savings ko protect karna.
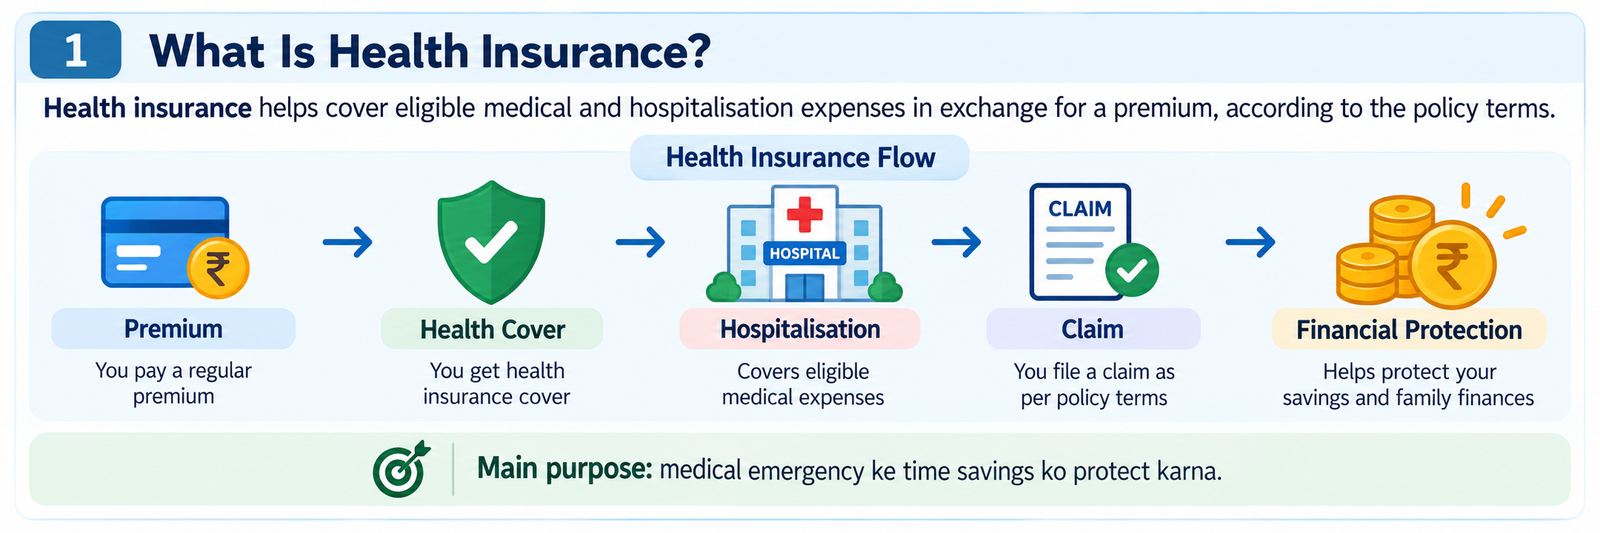
2. Why Do You Need It?
Medical treatment can be expensive.
💡 Simple Example
🏥 ₹5L Hospital Bill → 📋 Insurance Claim → 💰 Savings Protection
It can help protect:
- Savings
- Family finances
- Emergency fund
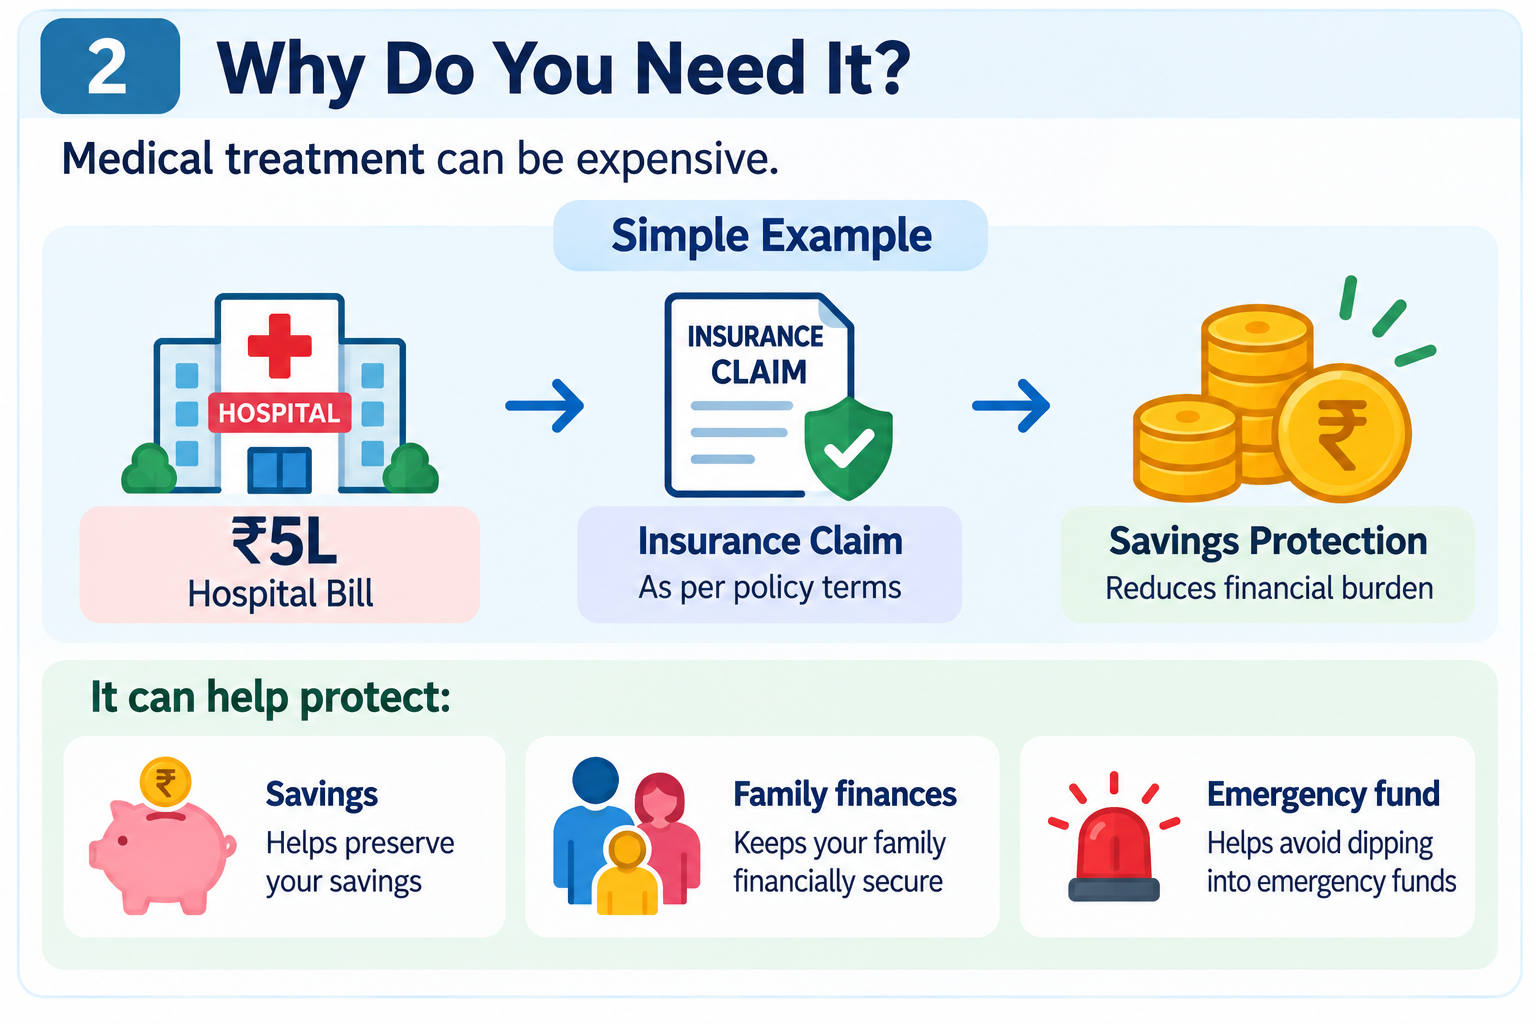
3. Individual vs Family Floater
👤 Individual → Separate Cover
👨👩👧 Family Floater → One Shared Cover
Family floater mein one sum insured covered family members ke beech share hota hai.
Quick Example
Individual: 👤 ₹5L + 👤 ₹5L
Floater: 👨👩👧 ₹10L Shared Pool
Choose based on:
Family Size + Age + Medical Needs + Budget
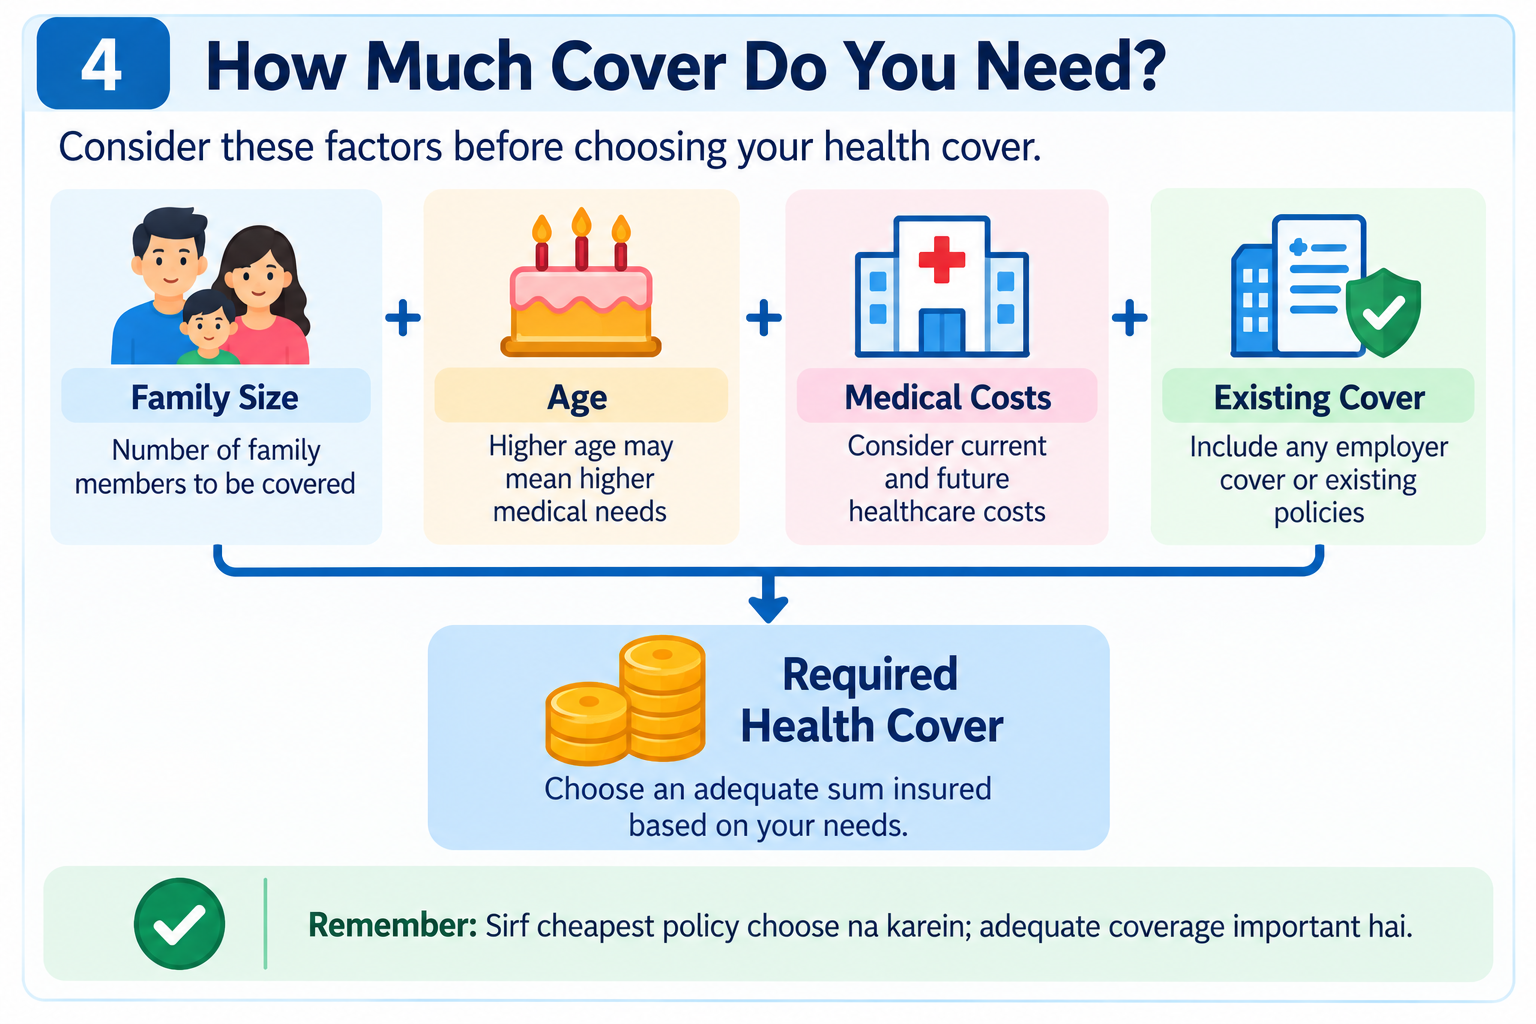
4. How Much Cover Do You Need?
Consider:
👨👩👧 Family Size + 🎂 Age + 🏥 Medical Costs + 🏢 Existing Cover
⬇️
💰 Required Health Cover
Sirf cheapest policy choose na karein; adequate coverage important hai.
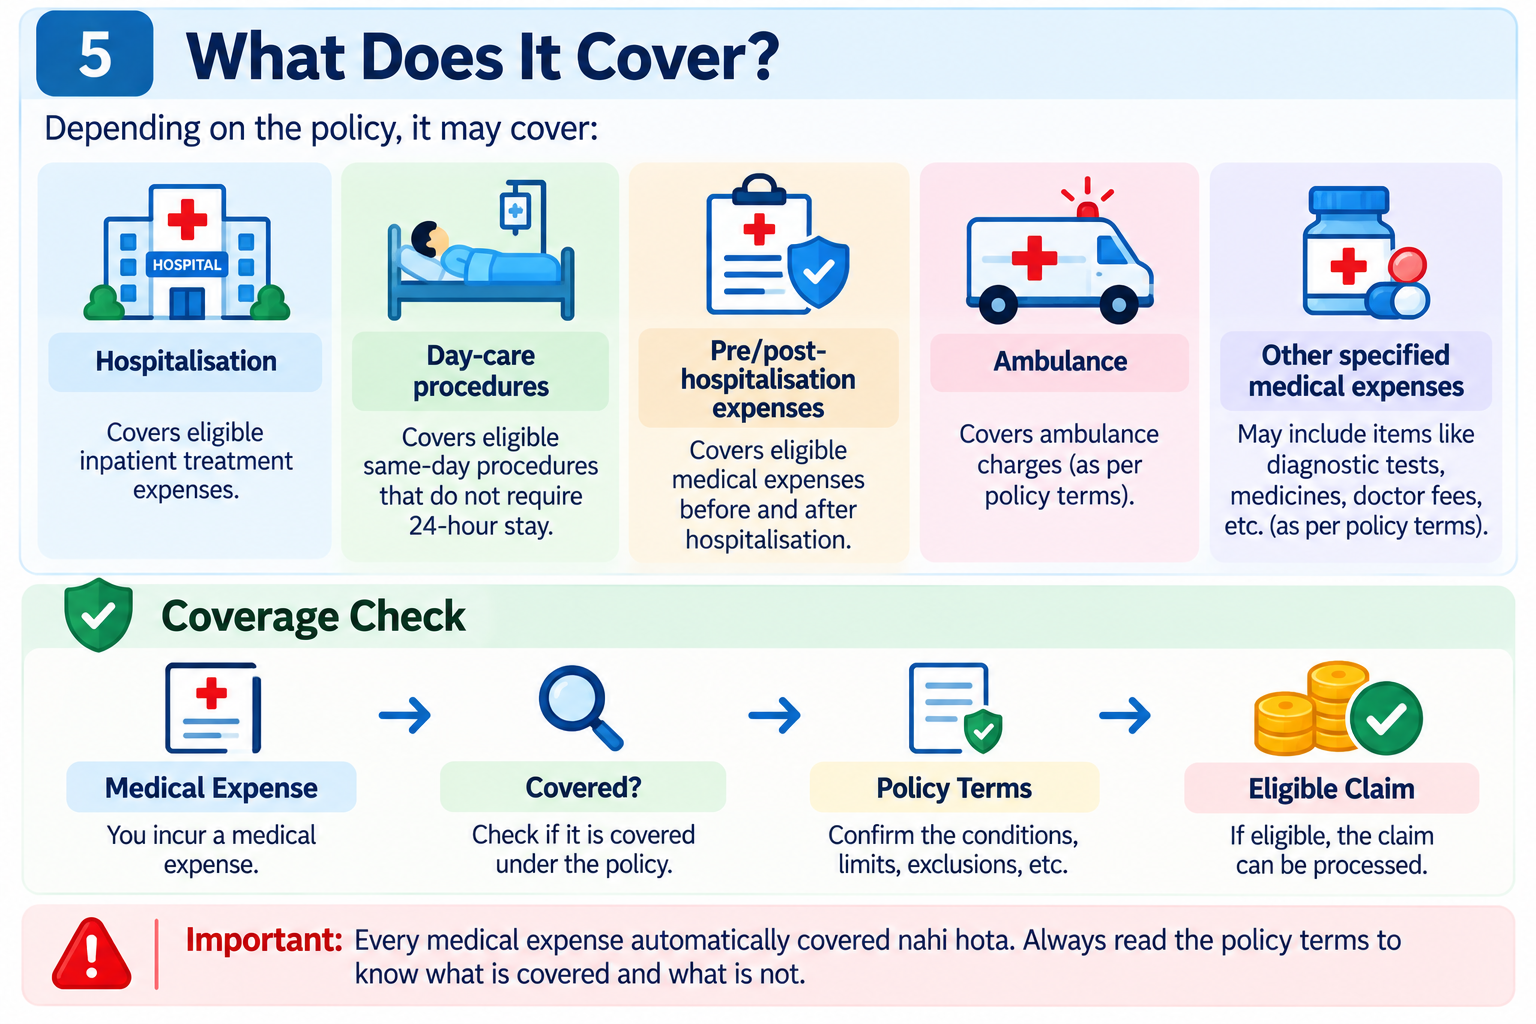
5. What Does It Cover?
Depending on the policy:
- Hospitalisation
- Day-care procedures
- Pre/post-hospitalisation expenses
- Ambulance
- Other specified medical expenses
🛡️ Coverage Check
Medical Expense → Covered? → Policy Terms → Eligible Claim
Every medical expense automatically covered nahi hota.
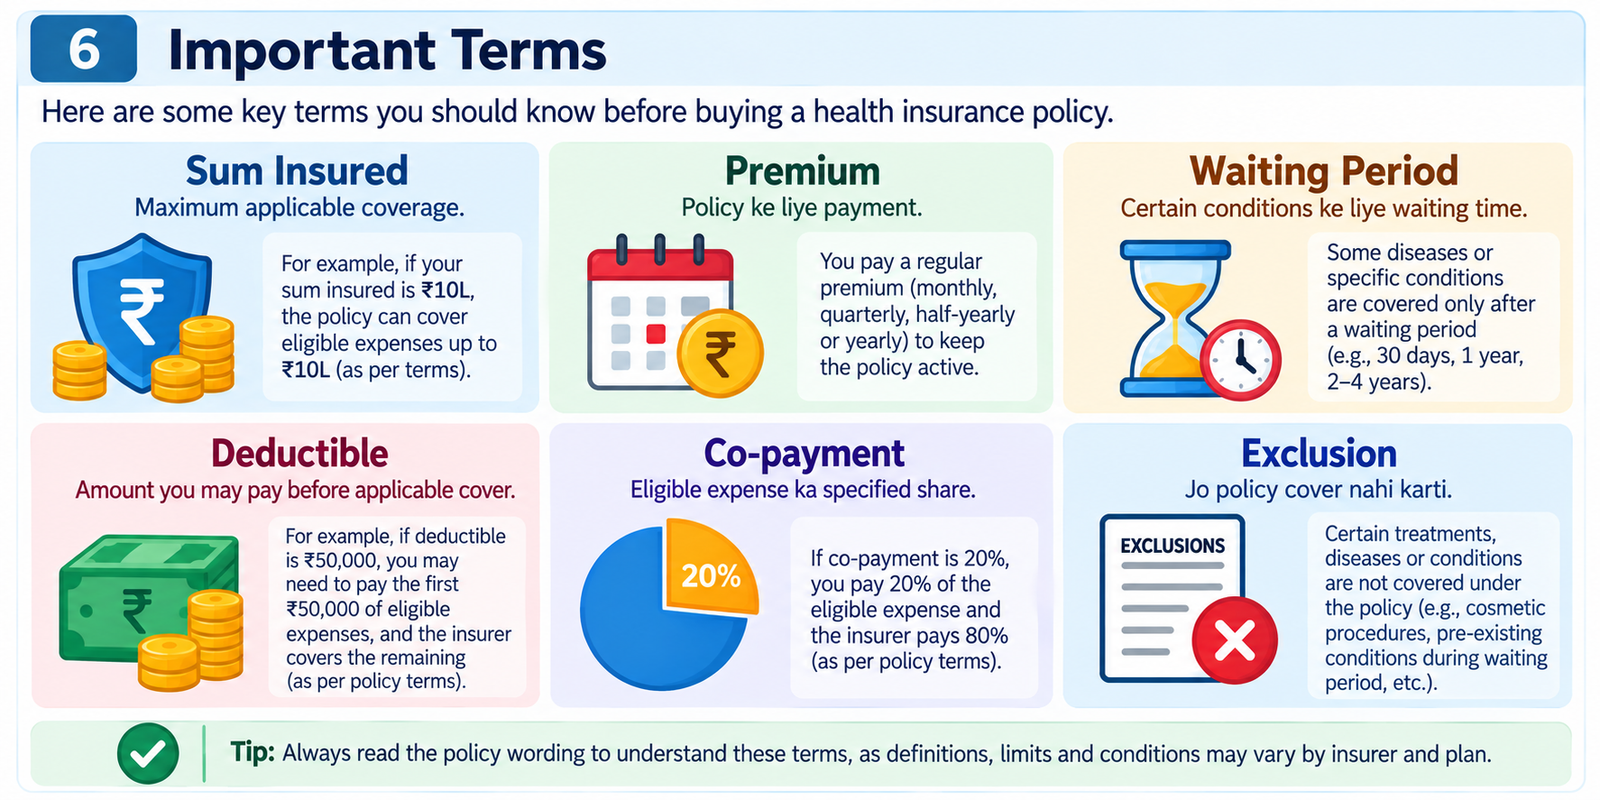
6. Important Terms
💰 Sum Insured → Maximum applicable coverage
💳 Premium → Policy ke liye payment
⏳ Waiting Period → Certain conditions ke liye waiting time
💵 Deductible → Amount you may pay before applicable cover
🤝 Co-payment → Eligible expense ka specified share
🚫 Exclusion → Jo policy cover nahi karti
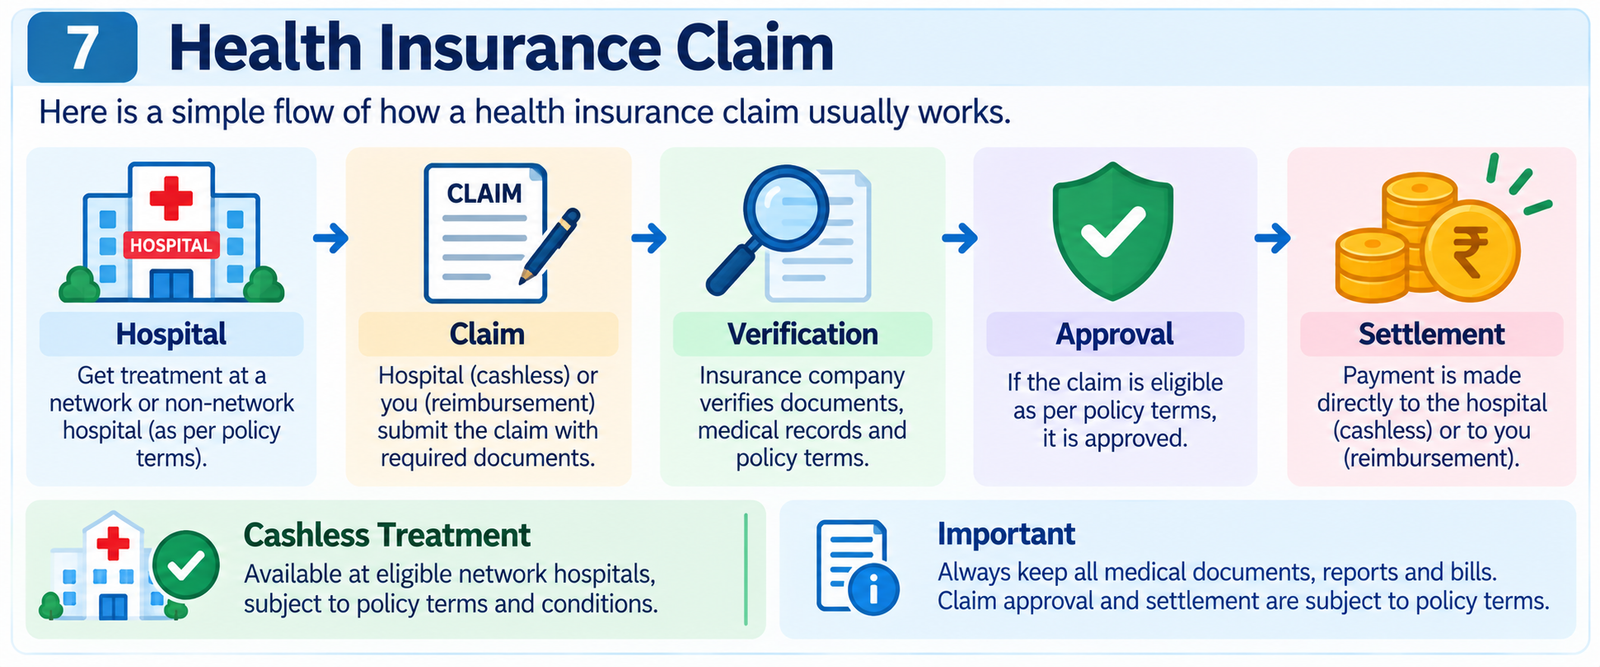
7. Health Insurance Claim
🏥 Claim Flow
🏥 Hospital → 📋 Claim → 🔎 Verification → ✅ Approval → 💰 Settlement
Cashless treatment eligible network hospitals par available ho sakta hai, subject to policy terms.
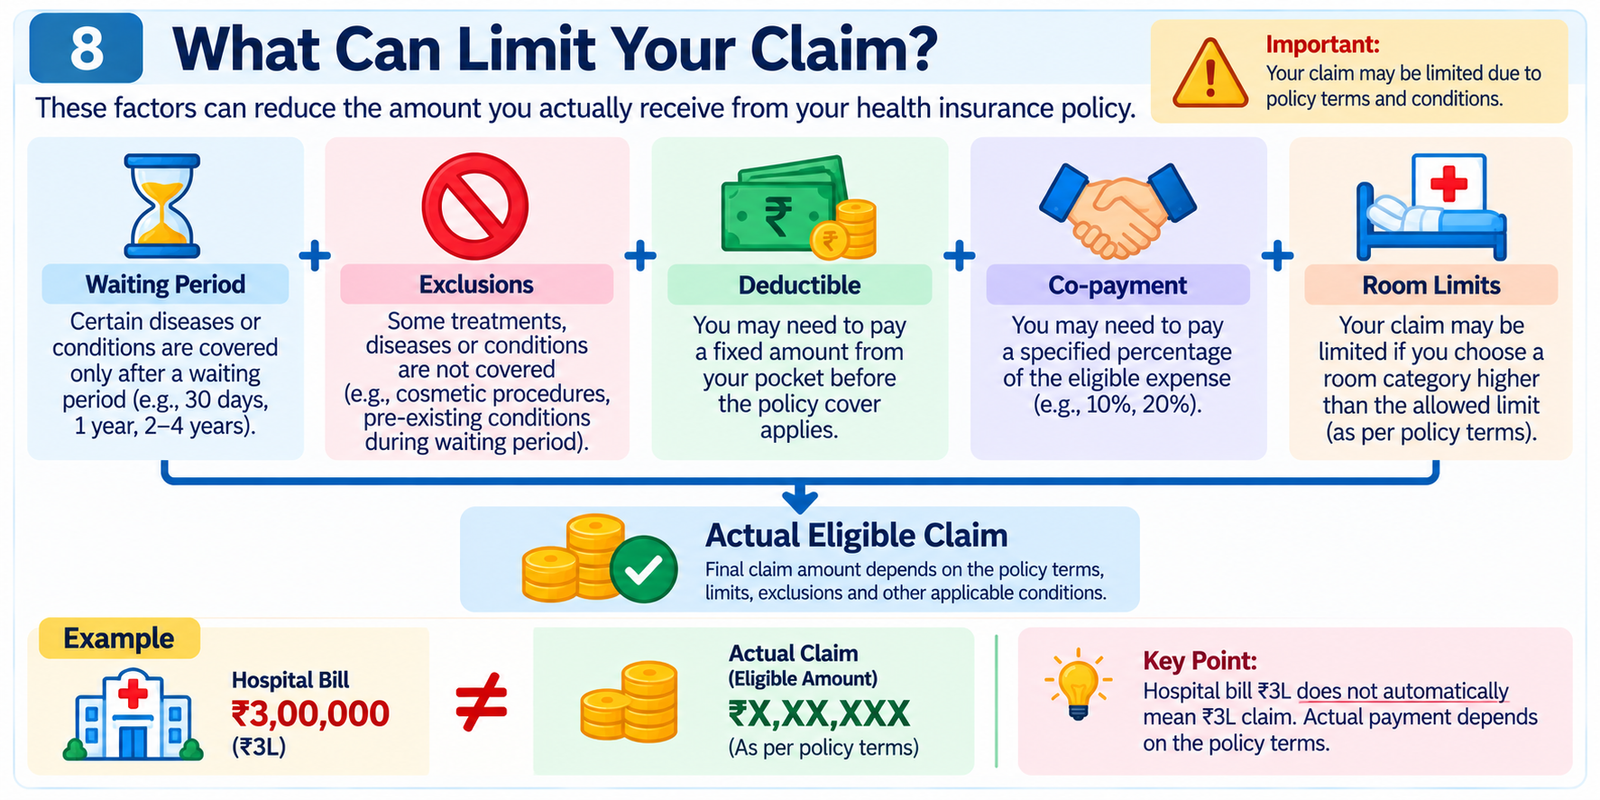
8. What Can Limit Your Claim?
⚠️ Important
⏳ Waiting Period + 🚫 Exclusions + 💵 Deductible + 🤝 Co-pay + 🏥 Room Limits
⬇️
Actual Eligible Claim
Example
Hospital Bill ₹3L ≠ Automatically ₹3L Claim
Actual payment policy terms par depend karega.
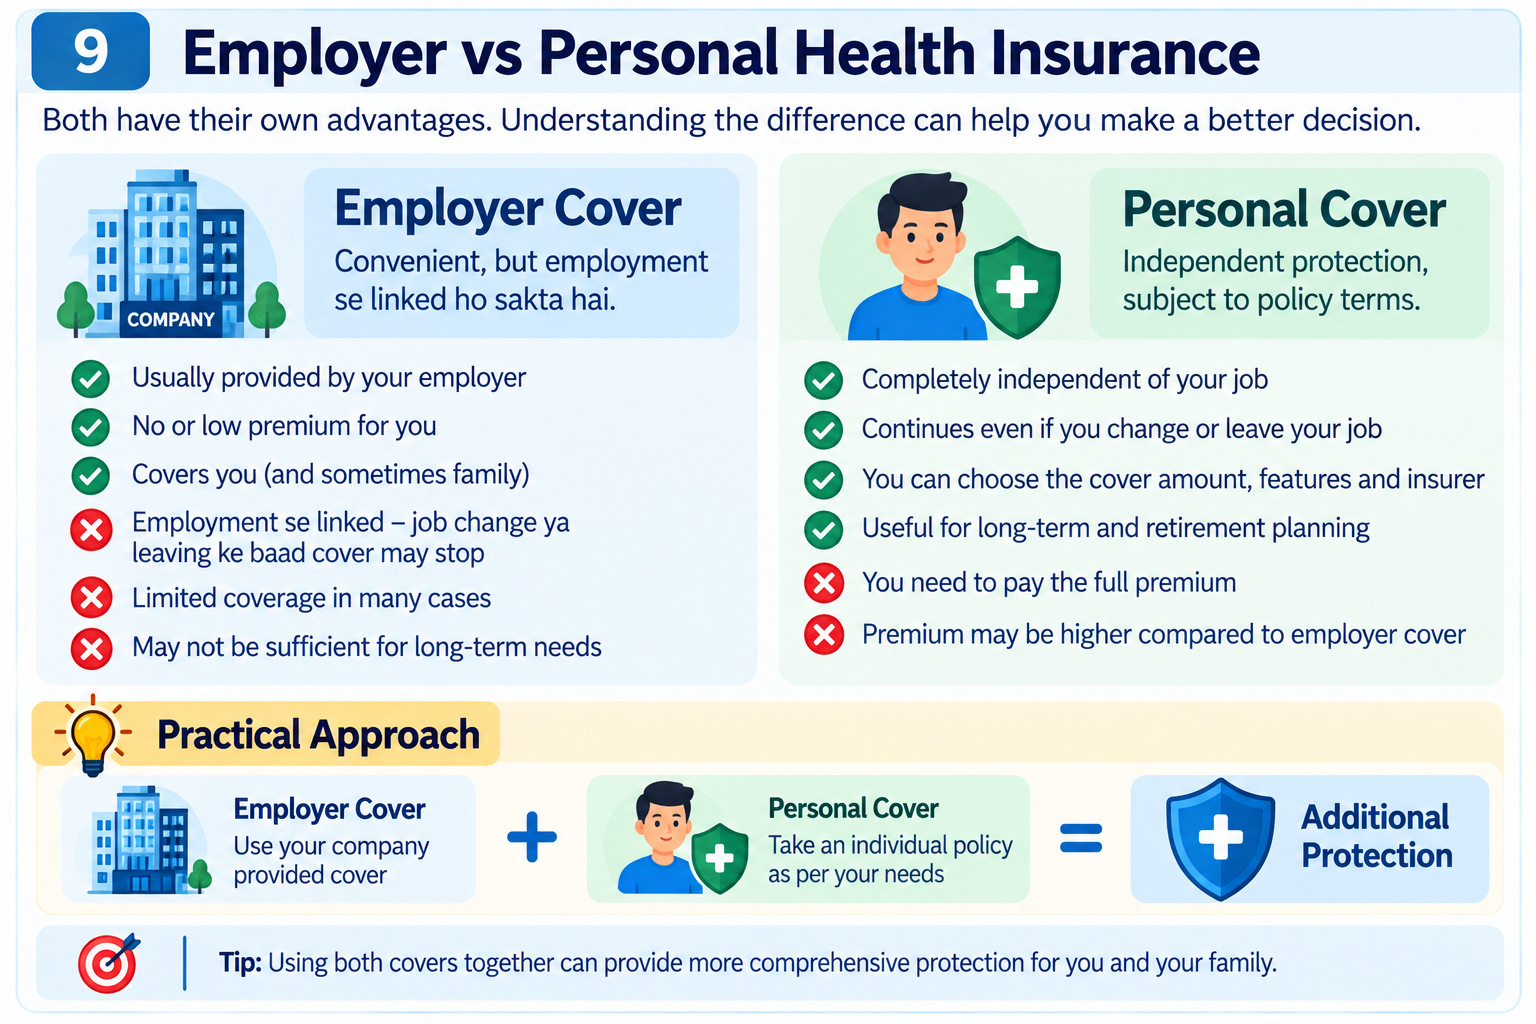
9. Employer vs Personal Health Insurance
🏢 Employer Cover
Convenient, but employment se linked ho sakta hai.
👤 Personal Cover
Independent protection, subject to policy terms.
💡 Practical Approach
Employer Cover + Personal Cover → Additional Protection
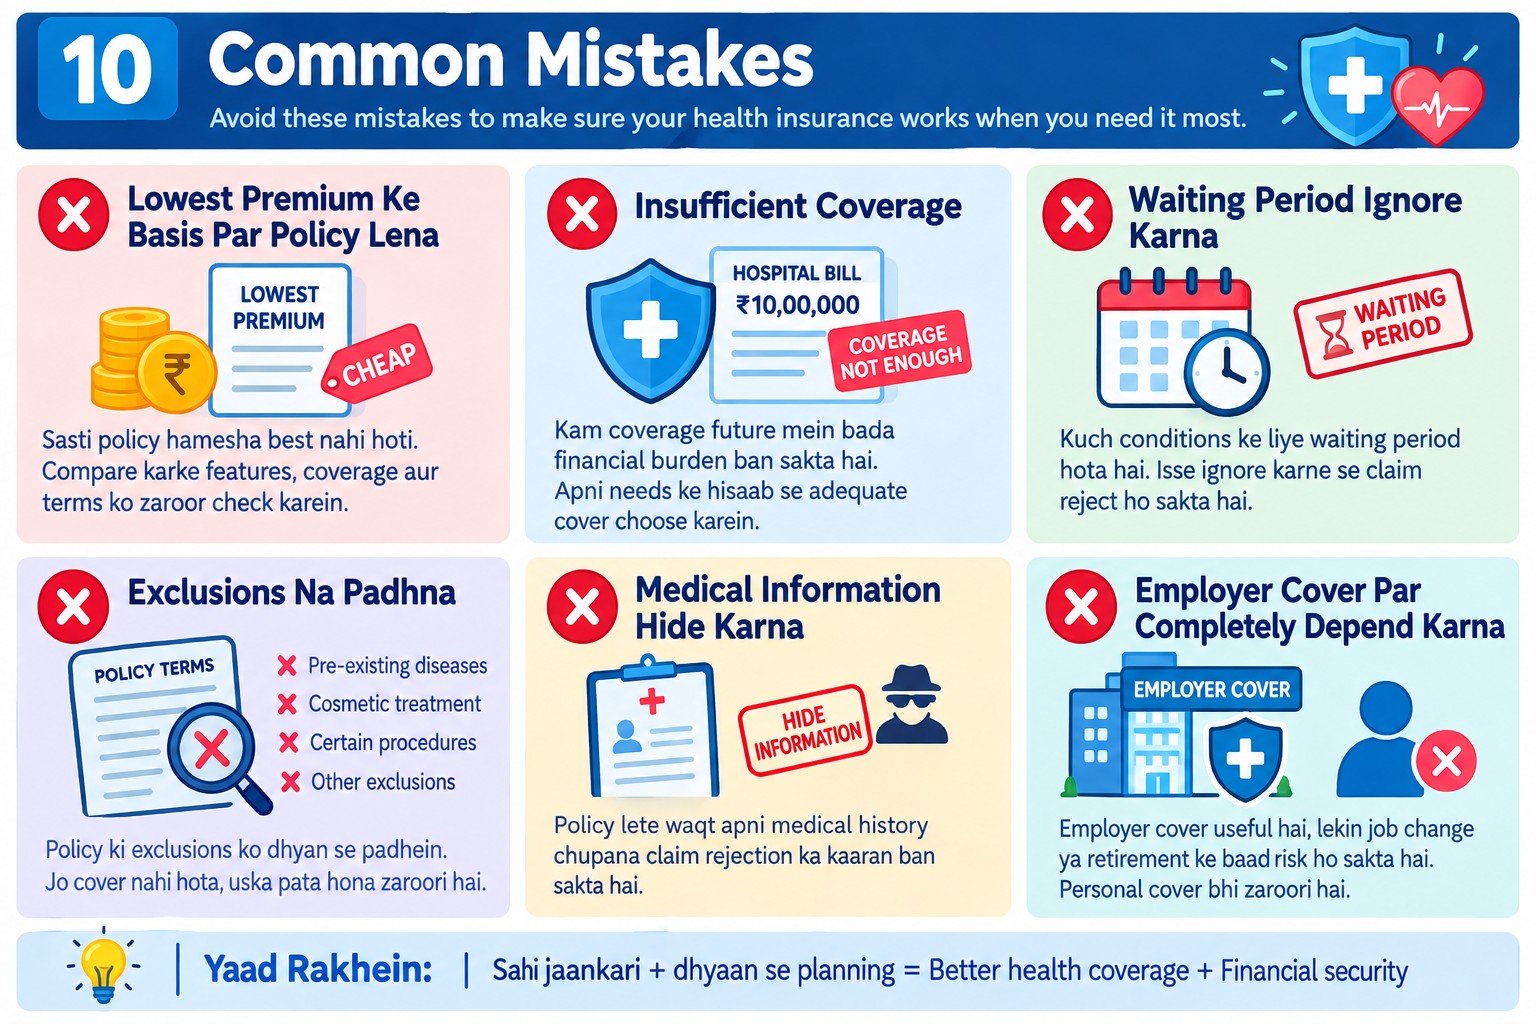
10. Common Mistakes
❌ Lowest premium ke basis par policy lena
❌ Insufficient coverage
❌ Waiting period ignore karna
❌ Exclusions na padhna
❌ Medical information hide karna
❌ Employer cover par completely depend karna
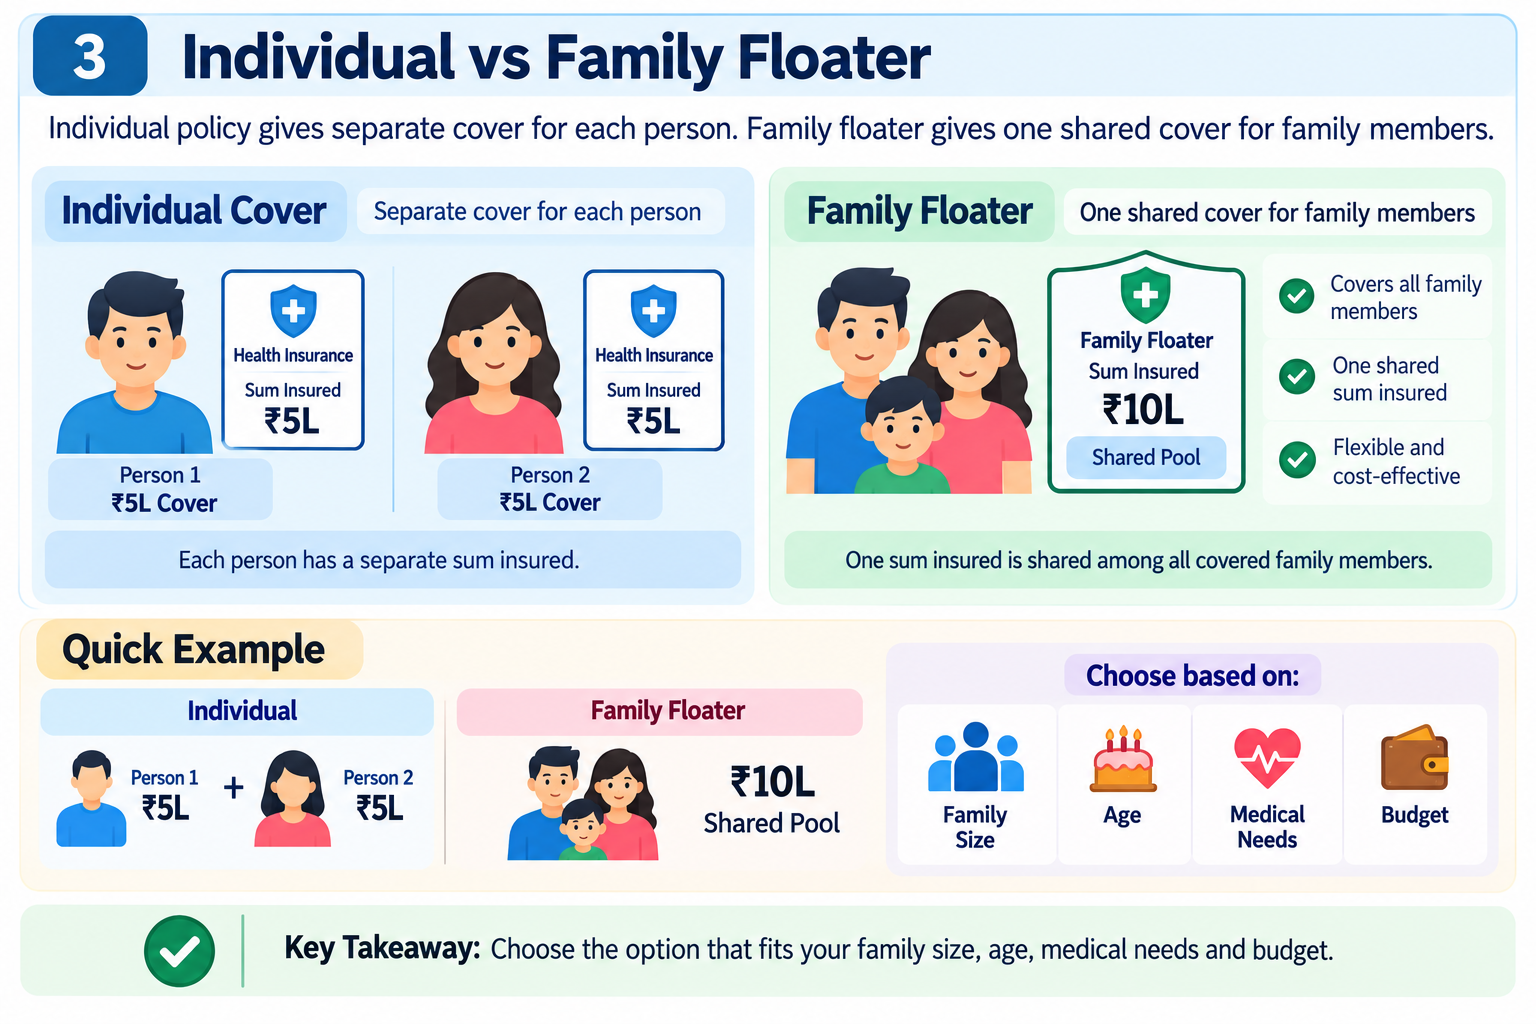
11. Paisonexa Practical Example 💙
👨👩👧 Family → 2 Adults + 1 Child
🏢 Employer Cover → ₹5L
⬇️
🏥 Medical Risk Check
⬇️
❓ Coverage Gap?
⬇️
🛡️ Personal Cover / Top-up Option
💙 Paisonexa Tip
Health insurance ka goal sirf policy lena nahi hai — goal hai serious medical expense ke time apni savings aur family finances ko protect karna.
Educational Note: Coverage, exclusions, waiting periods, limits, claims and premiums vary by policy. Always read the current policy wording before purchasing.