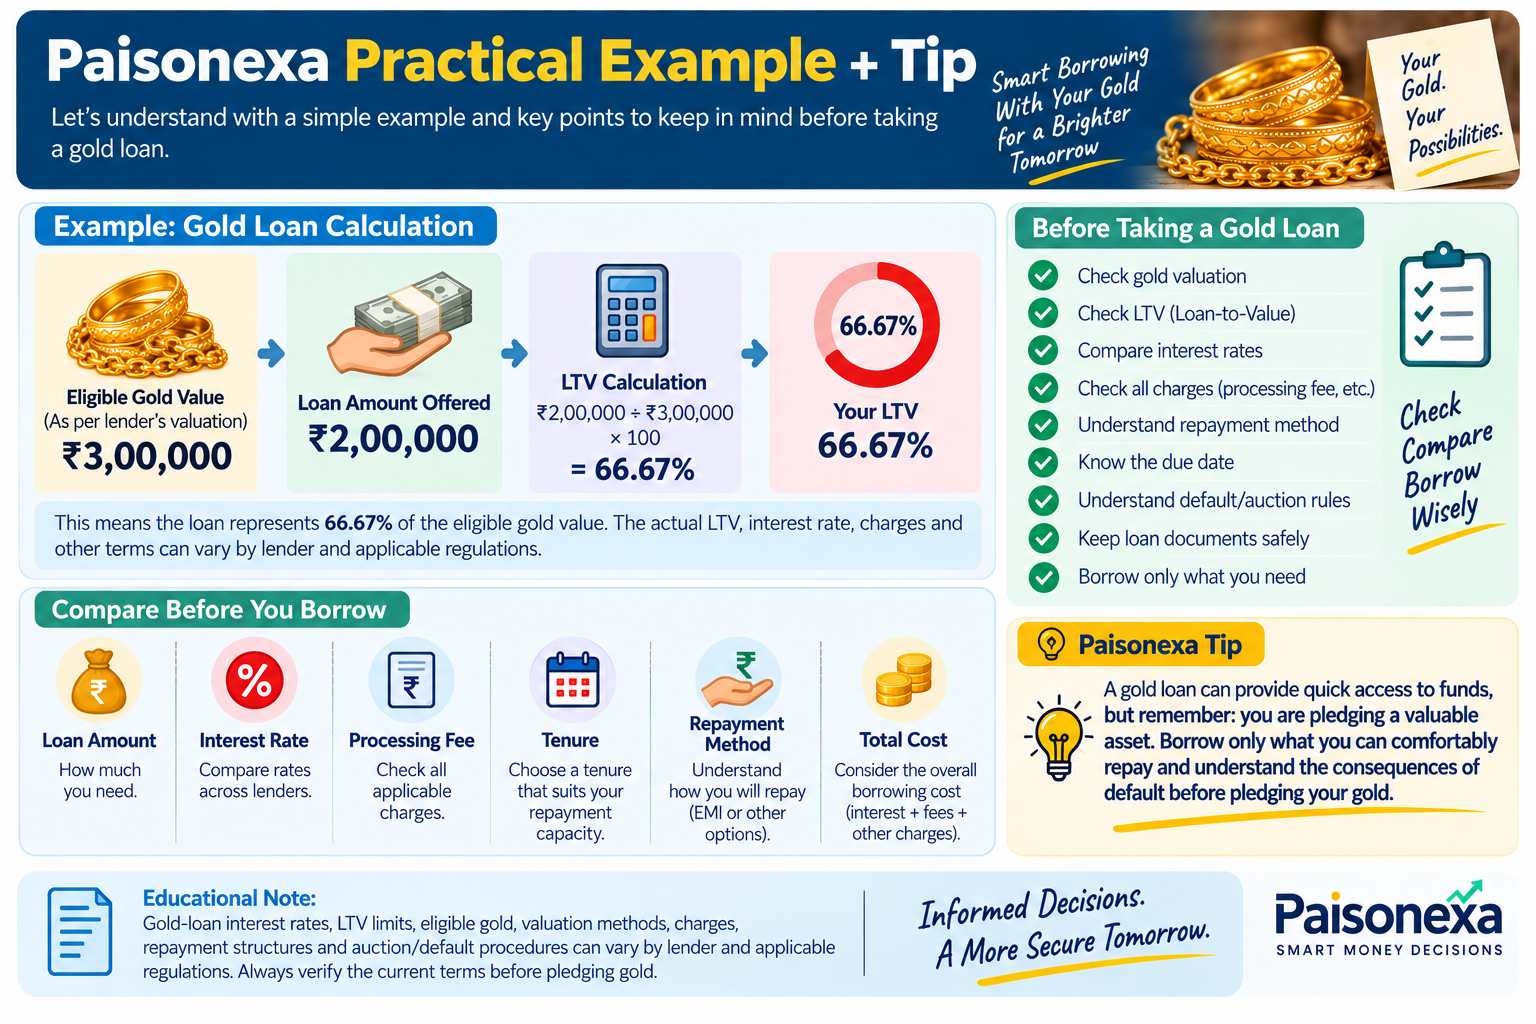
1. What Is a Gold Loan?
A gold loan is a secured loan where you pledge eligible gold jewellery or other permitted gold assets with a lender and receive a loan against them.
The gold remains with the lender as security until the loan is repaid according to the agreed terms.
Simple Example
Suppose the eligible value of your gold is:
₹2,00,000
The lender may offer a loan for only a portion of that value, depending on applicable Loan-to-Value (LTV) limits and the lender’s assessment.
Gold loan = Loan against pledged gold.
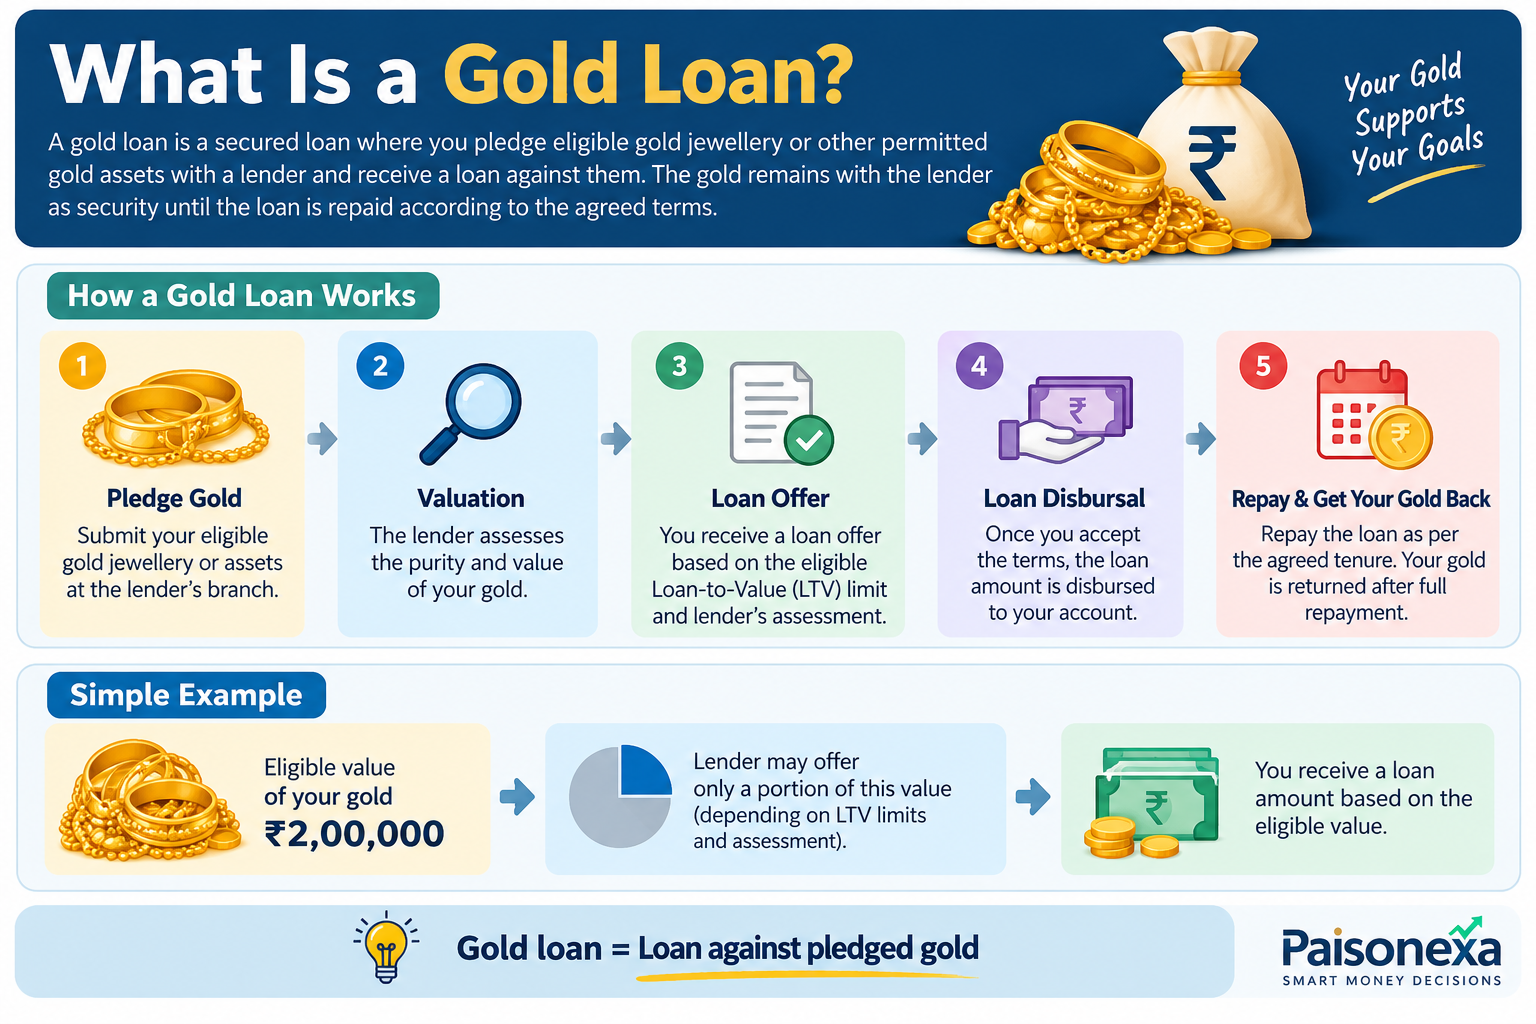
2. How Does a Gold Loan Work?
The basic process is:
Gold Assessment → Valuation → Loan Offer → Agreement → Gold Pledge → Disbursement → Repayment → Gold Release
The lender checks factors such as:
- Gold purity
- Eligible gold content
- Weight
- Applicable valuation rules
- Loan amount
- Repayment capacity and lender requirements
Once the loan is repaid according to the terms, the pledged gold is released to the borrower, subject to the lender’s process.
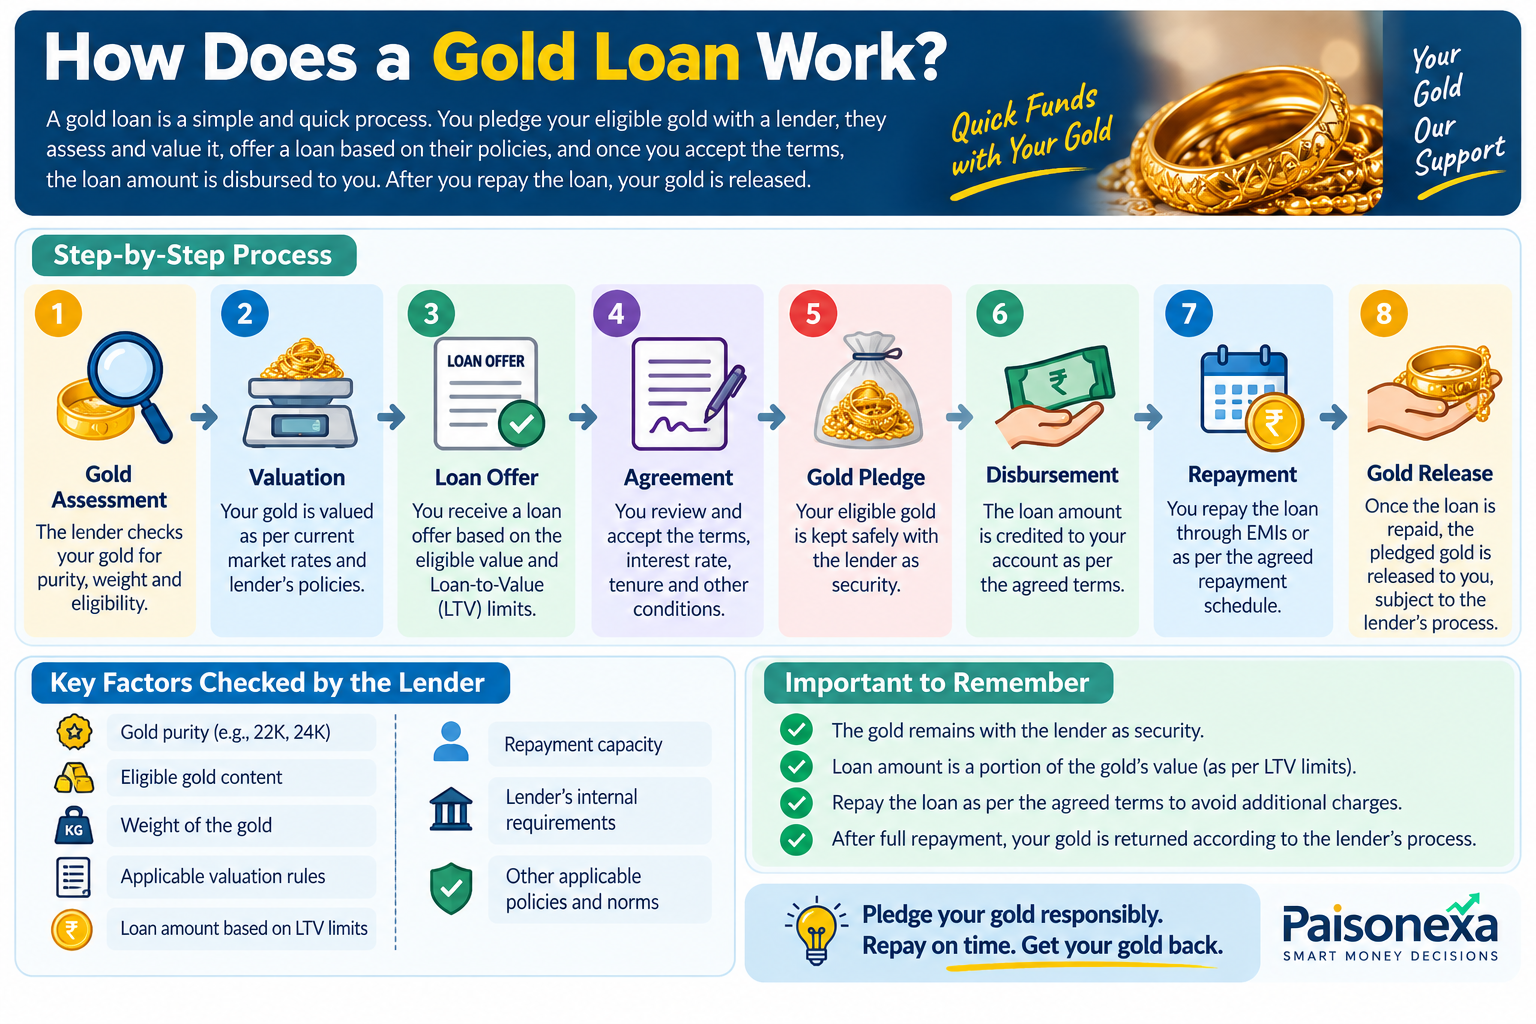
3. Loan Against Gold & LTV
LTV = Loan Amount ÷ Eligible Gold Value × 100
Example
Eligible gold value:
₹2,00,000
Loan amount:
₹1,40,000
LTV:
₹1,40,000 ÷ ₹2,00,000 × 100 = 70%
This means the loan represents 70% of the eligible gold value.
The maximum LTV allowed can depend on the applicable regulations, loan category and lender’s terms.
You should not assume that you will receive 100% of your gold’s market value as a loan.
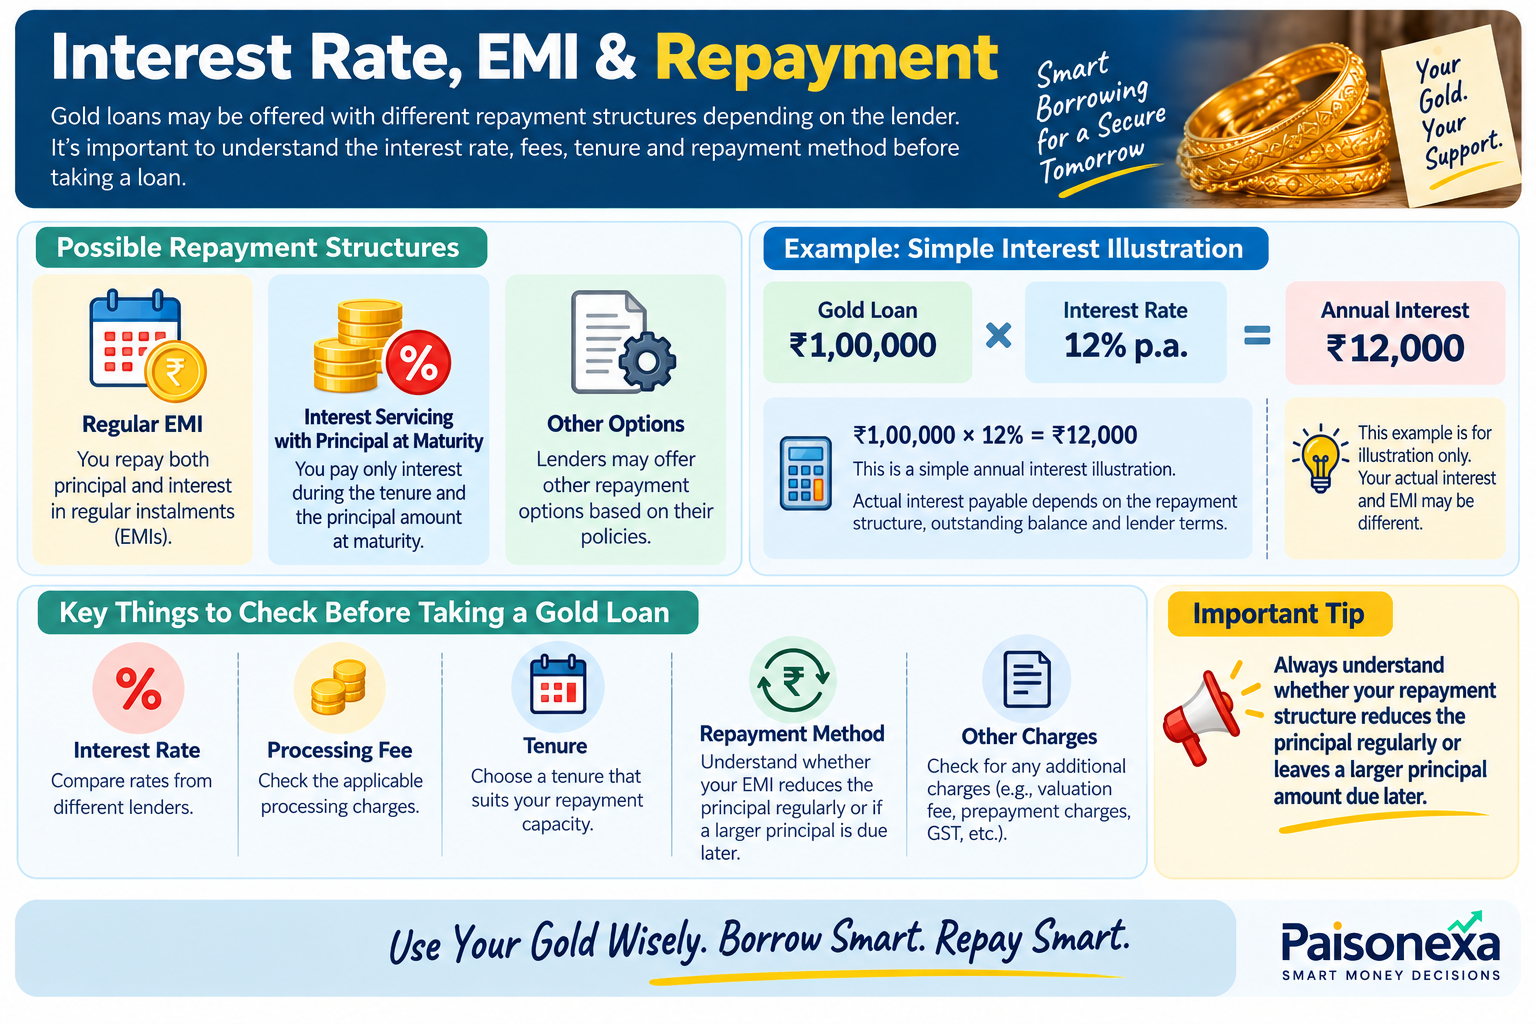
4. Interest Rate, EMI & Repayment
Gold loans may be offered with different repayment structures depending on the lender.
Possible structures can include:
- Regular EMI
- Interest servicing with principal repayment at maturity
- Other lender-specific repayment options
Example
Suppose:
Gold Loan = ₹1,00,000
Interest Rate = 12% p.a.
Simple annual interest illustration:
₹1,00,000 × 12% = ₹12,000
Actual interest payable depends on the repayment structure, outstanding balance and lender terms.
Before Taking the Loan
Check:
Interest Rate + Processing Fee + Tenure + Repayment Method + Other Charges
Always understand whether your repayment structure reduces the principal regularly or leaves a larger principal amount due later.
5. Gold Loan Eligibility & Process
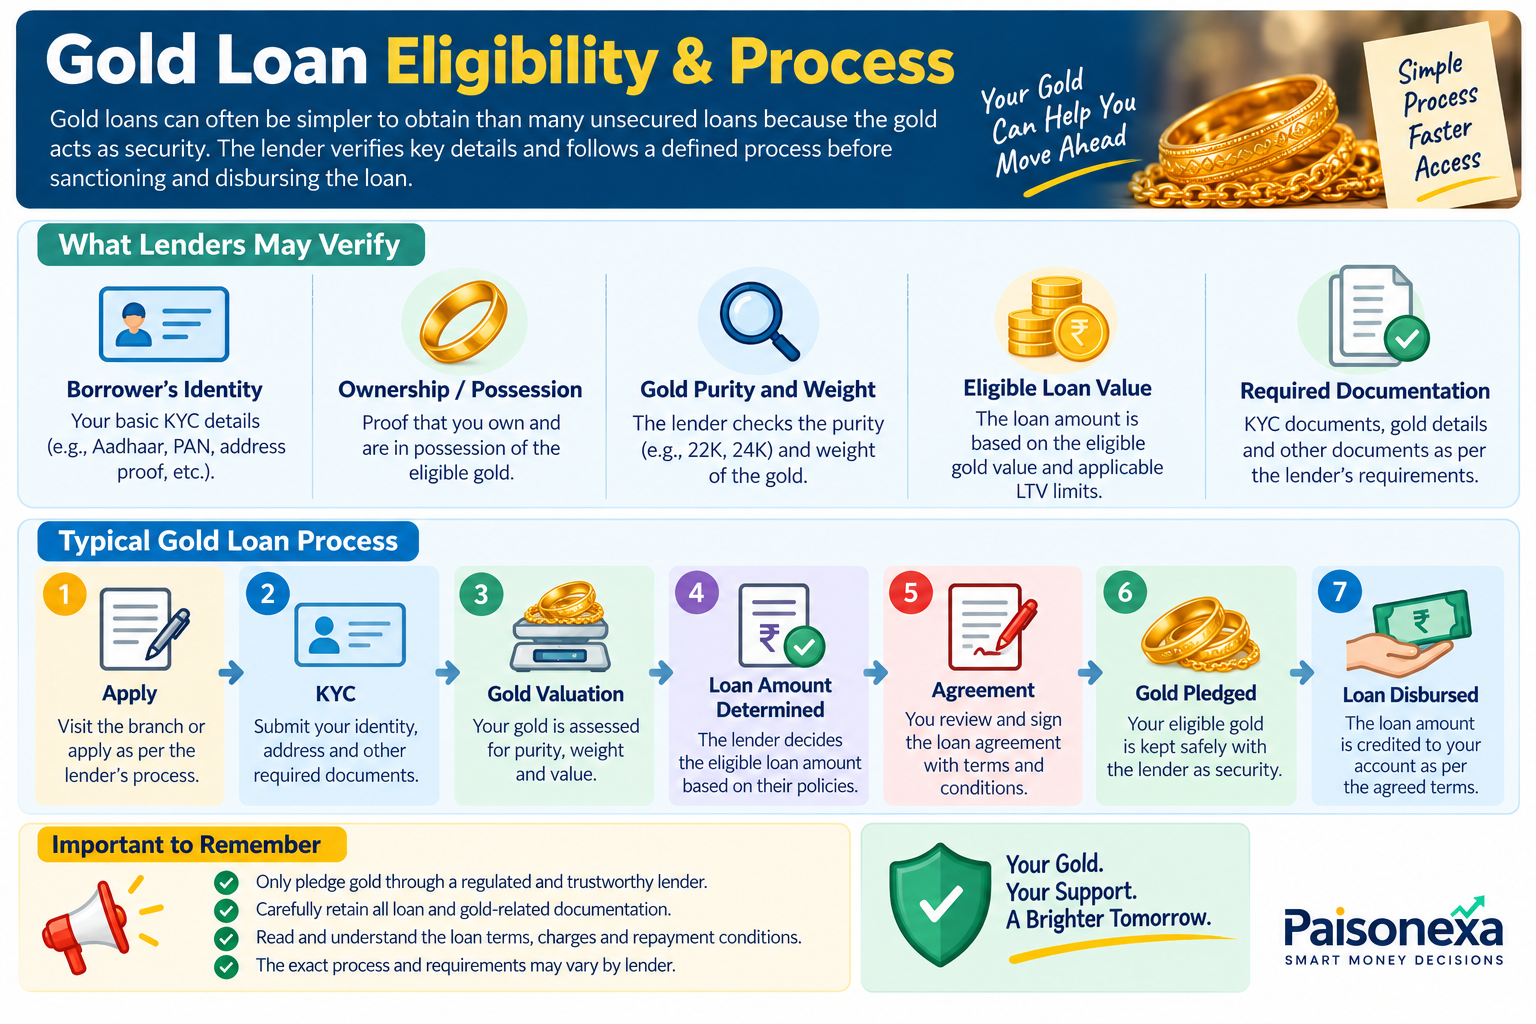
Gold loans can often be simpler to obtain than many unsecured loans because the gold acts as security.
The lender may verify:
- Borrower’s identity
- Ownership/possession of eligible gold
- Gold purity and weight
- Eligible loan value
- Required documentation
Typical Process
Apply → KYC → Gold Valuation → Loan Amount Determined → Agreement → Gold Pledged → Loan Disbursed
The exact process varies by lender.
Only pledge gold through a regulated and trustworthy lender, and carefully retain all loan and gold-related documentation.
6. Gold Loan vs Personal Loan
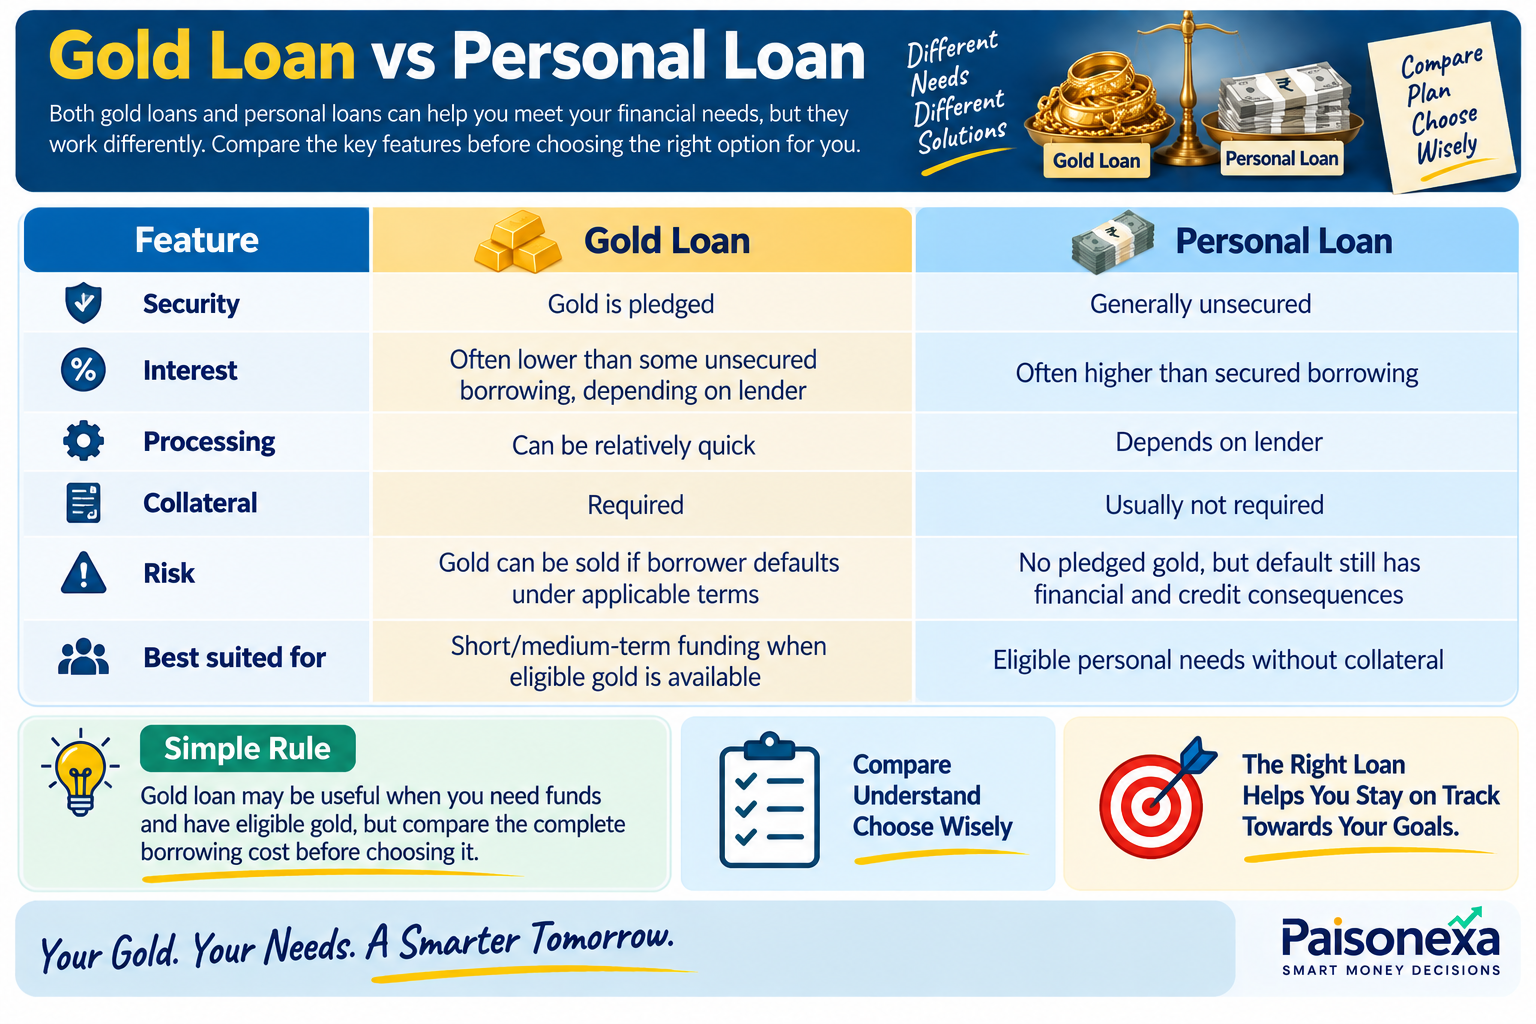
| Feature | Gold Loan | Personal Loan |
|---|---|---|
| Security | Gold is pledged | Generally unsecured |
| Interest | Often lower than some unsecured borrowing, depending on lender | Often higher than secured borrowing |
| Processing | Can be relatively quick | Depends on lender |
| Collateral | Required | Usually not required |
| Risk | Gold can be sold if borrower defaults under applicable terms | No pledged gold, but default still has financial and credit consequences |
| Best suited for | Short/medium-term funding when eligible gold is available | Eligible personal needs without collateral |
Simple Rule
Gold loan may be useful when you need funds and have eligible gold, but compare the complete borrowing cost before choosing it.
7. Default & Gold Auction Risk
This is the most important risk to understand.
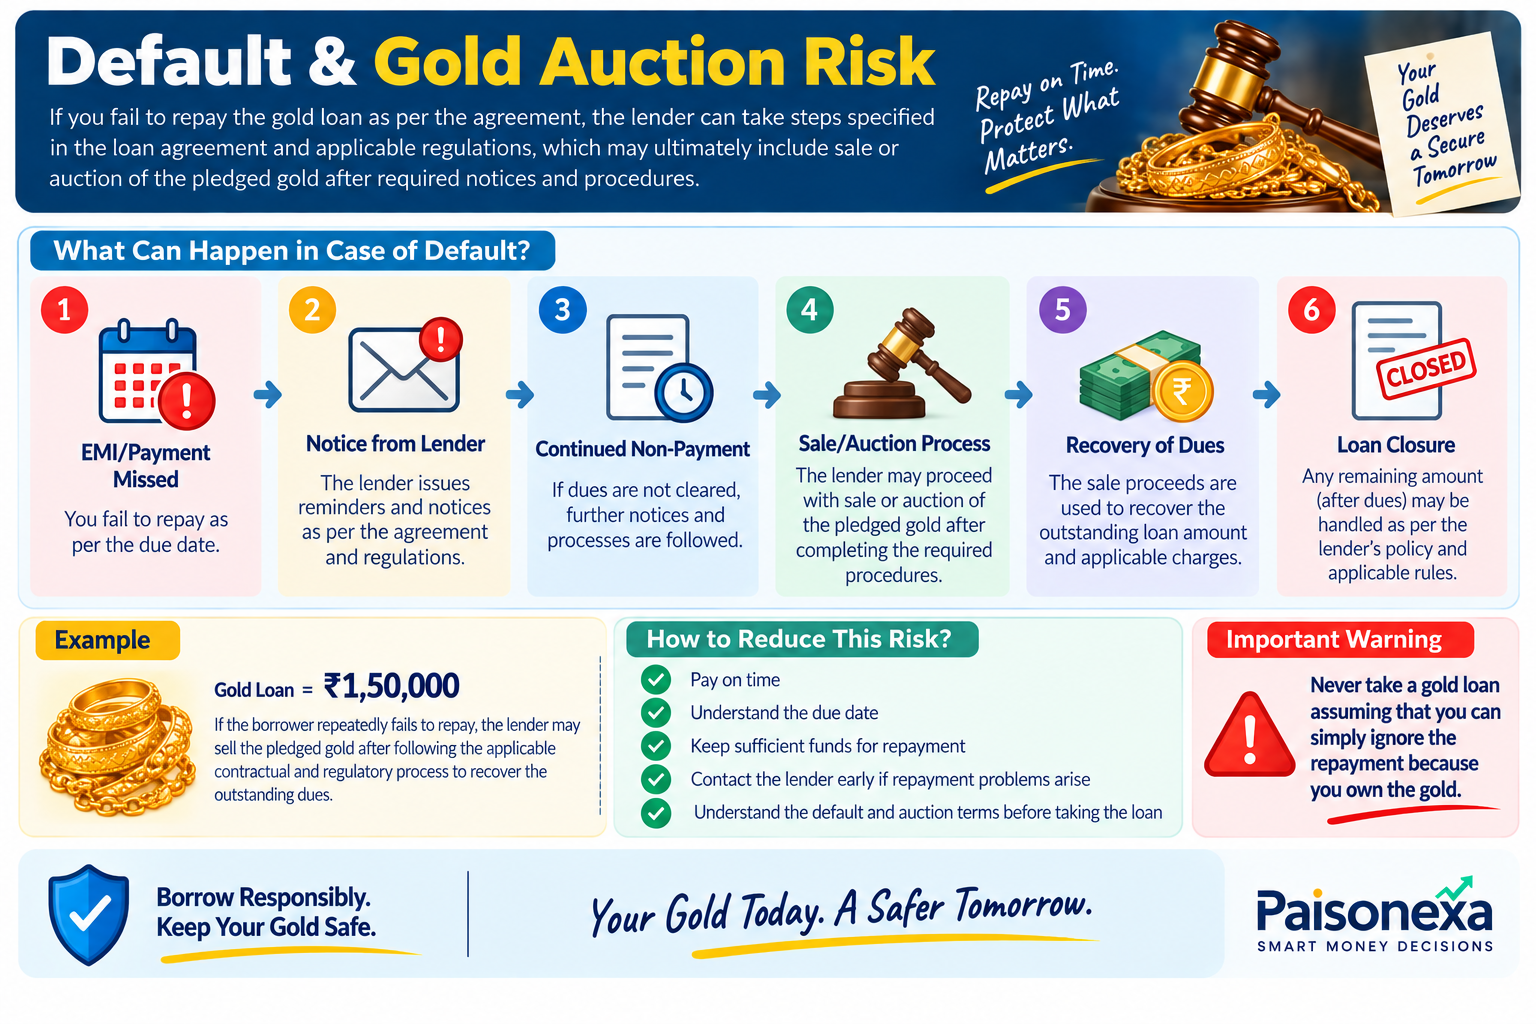
If the borrower fails to repay according to the loan agreement, the lender can take steps specified in the agreement and applicable regulations, which may ultimately include sale/auction of the pledged gold after required notices and procedures.
Example
Suppose:
Gold Loan = ₹1,50,000
The borrower repeatedly fails to repay.
After following the applicable contractual and regulatory process, the lender may sell the pledged gold to recover the outstanding dues.
How to Reduce This Risk
- Pay on time
- Understand the due date
- Keep sufficient funds for repayment
- Contact the lender early if repayment problems arise
- Understand the default and auction terms before taking the loan
Never take a gold loan assuming that you can simply ignore the repayment because you own the gold.
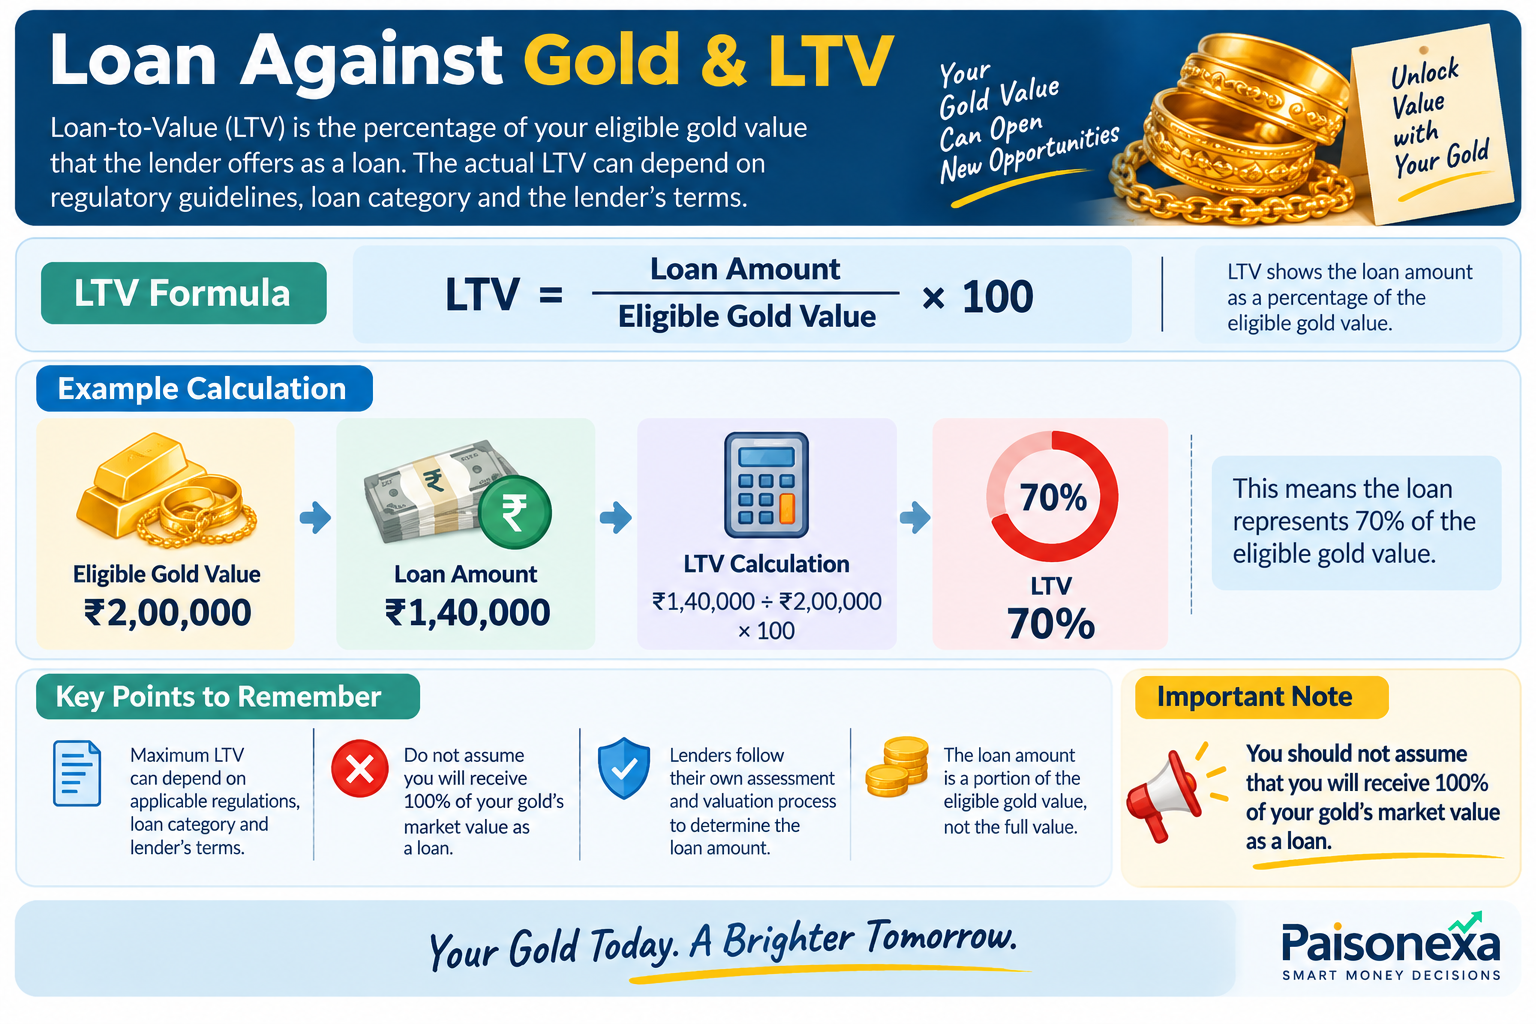
8. Paisonexa Practical Example + Tip 💙
Suppose you have eligible gold valued by the lender at:
₹3,00,000
The lender offers a loan of:
₹2,00,000
Your LTV is:
₹2,00,000 ÷ ₹3,00,000 × 100 = 66.67%
Now compare:
Loan Amount → Interest Rate → Processing Fee → Tenure → Repayment Method → Total Cost
If you can comfortably repay the loan and the borrowing is genuinely required, a gold loan may be considered.
Before Taking a Gold Loan
☑ Check gold valuation
☑ Check LTV
☑ Compare interest rates
☑ Check all charges
☑ Understand repayment method
☑ Know the due date
☑ Understand default/auction rules
☑ Keep loan documents safely
☑ Borrow only what you need
💙 Paisonexa Tip
A gold loan can provide quick access to funds, but remember: you are pledging a valuable asset. Borrow only what you can comfortably repay and understand the consequences of default before pledging your gold.
Educational Note: Gold-loan interest rates, LTV limits, eligible gold, valuation methods, charges, repayment structures and auction/default procedures can vary by lender and applicable regulations. Always verify the current terms before pledging gold.