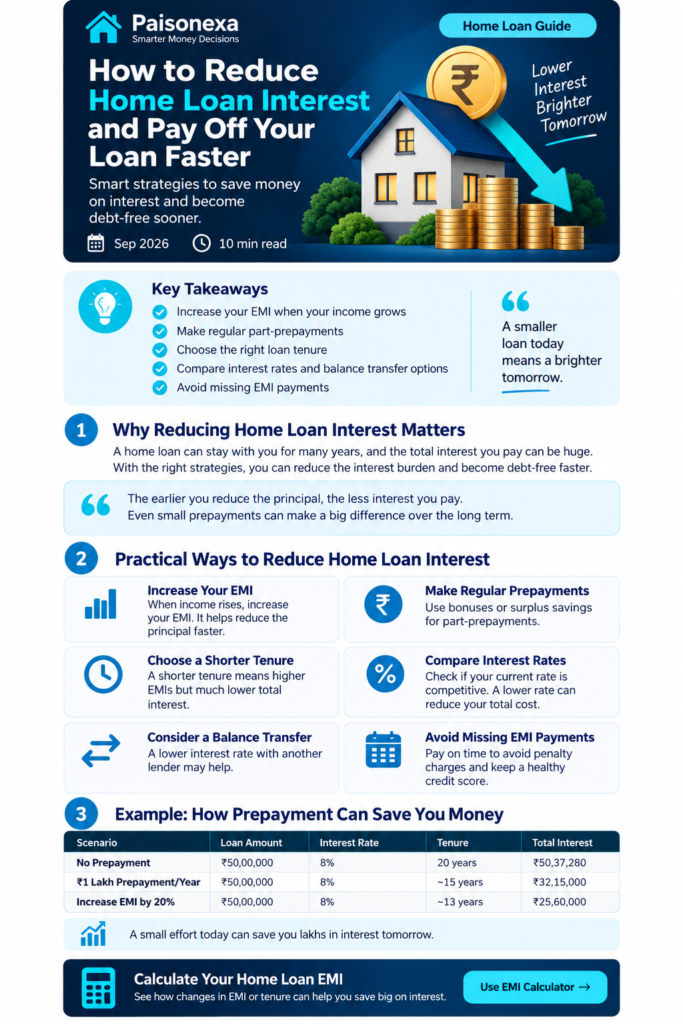
A home loan is a long-term commitment, but you can reduce your total interest burden with a few smart repayment strategies. The key is to reduce your outstanding principal faster while keeping your monthly finances comfortable.
Key Takeaways
✅ Increase EMI when income grows
✅ Make regular part-prepayments
✅ Choose a suitable loan tenure
✅ Review your interest rate
✅ Keep an emergency fund
1. Increase Your EMI
When your salary increases, consider increasing your EMI.
For example, moving from ₹40,000 to ₹45,000 can help you repay the principal faster.
Income increases → EMI increases → Loan reduces faster
2. Make Regular Prepayments
Use a portion of bonuses, incentives or genuine surplus savings for home-loan prepayment.
Even smaller, regular prepayments can help reduce the outstanding principal and future interest.
Important: Don’t use your entire emergency fund for prepayment.
3. Choose the Right Tenure
A longer tenure generally means a lower EMI but a higher overall interest cost.
A shorter tenure generally means a higher EMI but can reduce the total interest paid.
Choose a tenure that fits your monthly cash flow.
4. Compare Interest Rates
Review your current home-loan rate from time to time.
Before switching lenders, compare:
- Interest rate
- Outstanding loan
- Remaining tenure
- Processing/switching charges
- Overall savings
A lower advertised rate doesn’t automatically mean a better deal.
5. Prepayment vs Investing
Paying down the loan reduces your future interest cost.
Investing can potentially generate higher long-term returns, but investment returns are not guaranteed.
A balanced approach can be:
Regular investing + Planned home-loan prepayments
Simple Example
Suppose:
Loan: ₹50 lakh
Interest: 8%
Tenure: 20 years
A borrower could combine:
Regular EMI + ₹1 lakh annual prepayment + EMI increases after salary hikes
The actual savings will depend on the outstanding principal, timing of prepayments and loan terms.
Mistakes to Avoid
❌ Using the entire emergency fund
❌ Taking an EMI that is too high
❌ Looking only at the interest rate
❌ Stopping all investments
❌ Ignoring other high-interest debt
Calculate Your EMI
Before changing your EMI or planning a prepayment, use the Paisonexa EMI Calculator to understand your repayment.
EMI Calculator →
https://paisonexa.com/financial-calculators/emi-calculator/
Final Takeaway
The fastest way to reduce your home-loan burden is not necessarily one huge payment.
A better approach is:
Increase EMI + Make regular prepayments + Review your loan + Protect your emergency fund
Less Interest. Less Debt. More Financial Freedom.
FAQs
Can increasing EMI reduce home-loan interest?
Yes. It can help reduce the principal faster and therefore may reduce future interest.
Is prepayment always better?
Not necessarily. Consider your emergency fund, investments, liquidity and other debts.
Should I choose a shorter tenure?
A shorter tenure can reduce total interest, but the EMI will generally be higher.
Should I prepay or invest?
It depends on your loan rate, investment risk and financial goals. A combination can also work well.